Finance
Can Hezbollah’s shadow economy be dismantled?

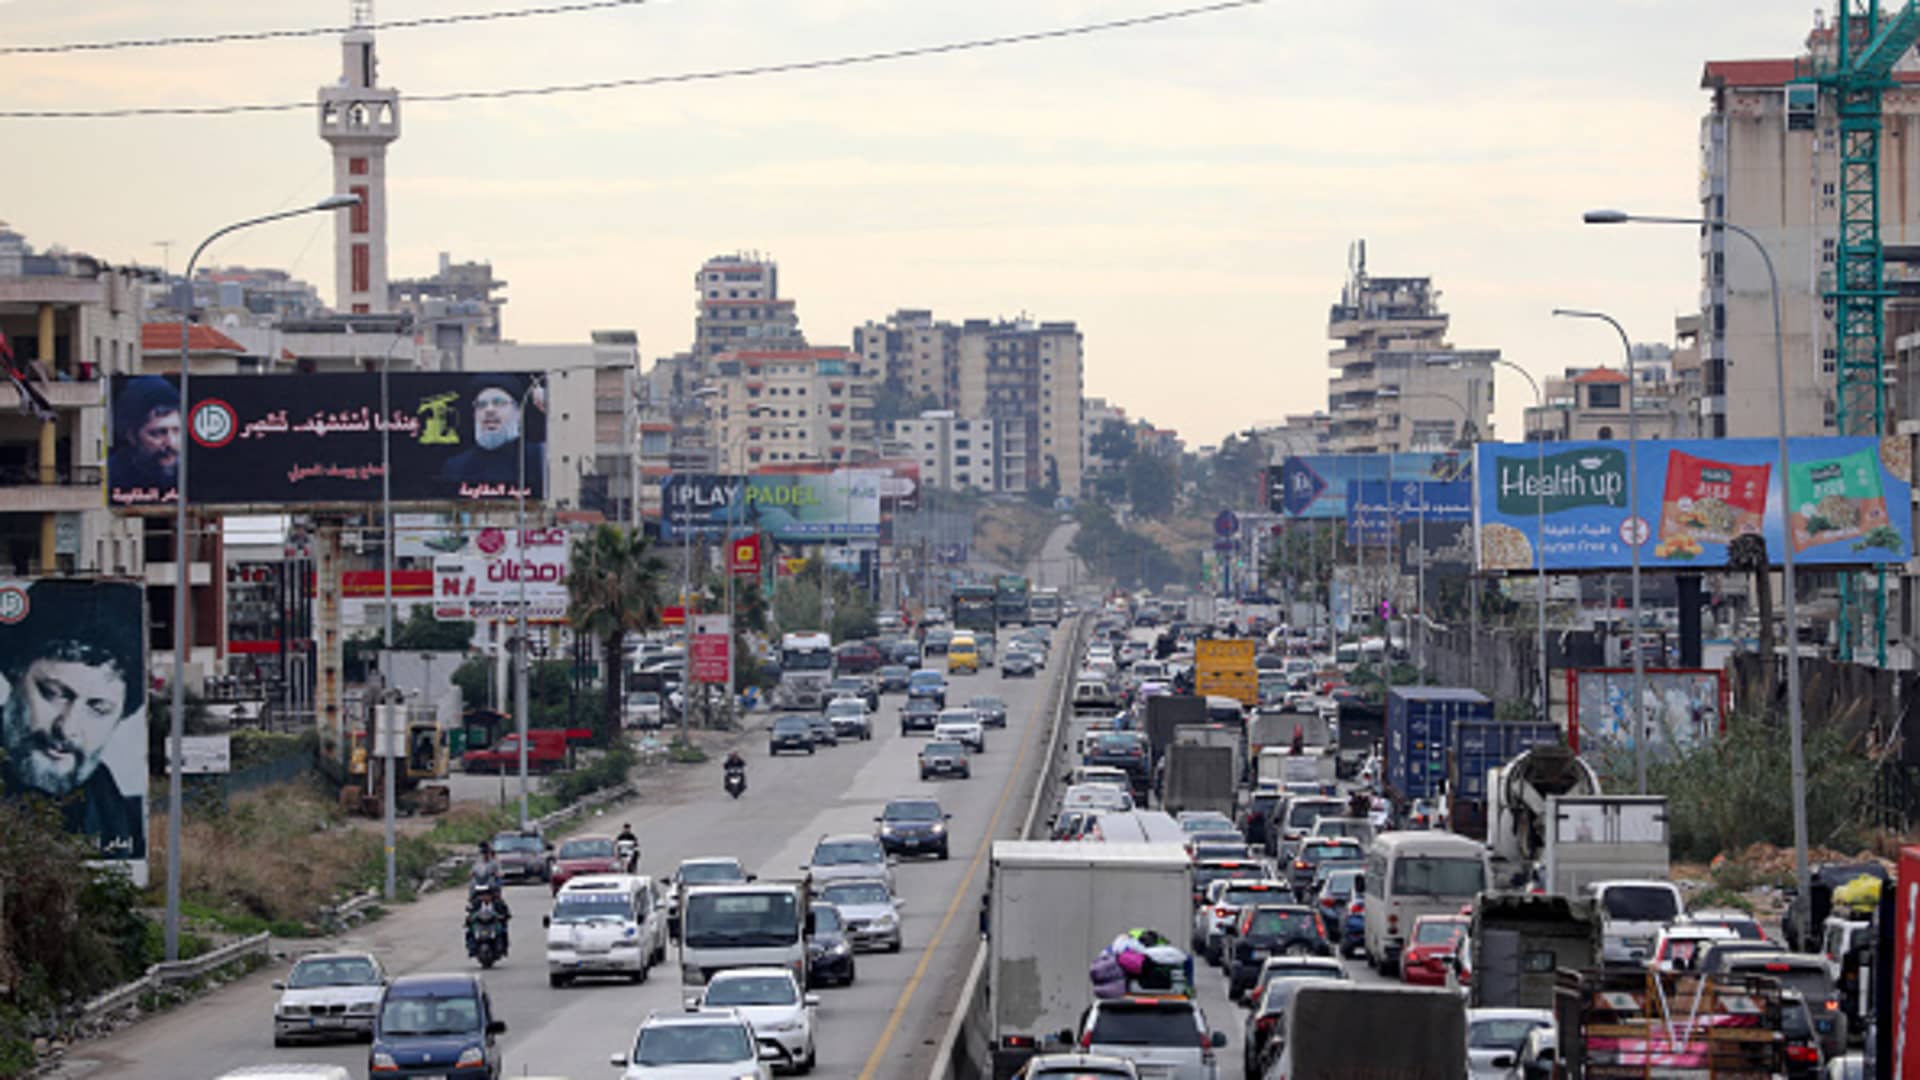
Vehicles transporting people who had fled southern Lebanon are slowed down by heavy traffic on the outbound road from Beirut, in the area of Khaldeh on November 28, 2024, a day after a cease fire between Israel and Hezbollah took hold.
Ibrahim Amro | Afp | Getty Images
Up until a few months ago, the drive from Beirut’s international airport through the Lebanese capital city’s southern suburbs used to feature a stream of pro-Iranian and Hezbollah-themed propaganda.
Hassan Nasrallah, the charismatic former leader of the Iran-backed group who was killed in Beirut last year, stared down at you from billboards while you drove along Imam Khomeini Road, named after the late founder of Iran’s Islamic Republic. Images of Hezbollah leaders were interspersed with dramatic murals of fallen Iranian spy commander Qasem Soleimani.
Now many of those images have been replaced with western and local brands. In June dozens of those billboards along the highway instead featured Formula One racecar driver Lewis Hamilton advertising shaving products.
Many of the new posters also feature patriotic, unifying messages that replaced the formerly sectarian signage — an attempt by Lebanon’s new Prime Minister Nawaf Salam to encourage “A New Era for Lebanon,” just in time for the summer tourism boom the Mediterranean country is hoping for after months of war.
In this “new” Lebanon, Hezbollah is being forced to operate in the shadows — more than ever in the group’s over 40-year history.
The Iranian proxy, which controls several parts of Lebanon as a sub-state group and is designated a terrorist organization by Washington, has always looked for creative ways to evade U.S. sanctions. But since Israel’s aggressive assault – its most deadly since the 2006 war – Hezbollah’s leadership and financial infrastructure have been left in tatters.
“Hezbollah finds itself in its greatest predicament since its foundation. The Israeli war against Lebanon greatly hit the party and its infrastructures, assassinating the party’s senior military and political leaders including Secretary-General Hassan Nasrallah,” Joseph Daher, author of “Hezbollah: The Political Economy of Lebanon’s Party of God,” told CNBC.
“The regions majorly inhabited by the Shia population have been greatly targeted, destroying extensively civilian housing and infrastructures as well,” he said.
A vehicle carries the coffins of former Hezbollah leaders Hassan Nasrallah and Hashem Safieddine, who were killed in Israeli airstrikes last year, during a public funeral ceremony, in Camille Chamoun Sports City Stadium, on the outskirts of Beirut, Lebanon, on Feb. 23, 2025.
Thaier Al-sudani | Reuters
The group, whose political wing also holds seats in parliament, still wields significant political power in Lebanon, which last held parliamentary elections in 2022. Despite losing the most significant number of seats in the group’s political history, it still held tight to a 62-seat coalition in the 128-member parliament.
While Hezbollah “will not disappear because it has a strong, disciplined and organized political and militant structure, and benefits from the continued assistance of Iran,” the group “has become increasingly politically and socially isolated outside Lebanon’s Shia population,” Daher said.
Outside the banking system
While Hezbollah receives much of its funding from Iran, it has also developed extensive international financial networks to bring in revenue. The group makes money from traditional industries like banking and construction, but it also runs smuggling, money laundering and international drug trafficking operations around the Middle East and as far afield as Bulgaria and Argentina. Its revenues are estimated in the billions of dollars annually.
FILE PHOTO: Lebanon’s Hezbollah leader Sayyed Hassan Nasrallah gestures as he addresses his supporters during a rare public appearance at an Ashoura ceremony in Beirut’s southern suburbs November 3, 2014.
Hasan Shaaban | Reuters
Hezbollah’s parallel governance strategy, operating as both a political party and sub-state group, has enabled it to survive and grow as an armed group for decades.
When Lebanese depositors were locked out of their savings in 2019 after a financial meltdown crippled the country and its currency, Hezbollah remained able to fund its base and illicit activities. It operated cash-only businesses and ran black market U.S. dollar exchanges.
This strategy will continue despite pressure on their finances, regional analysts say, due to the extreme difficulty of tracking informal, cash-only transactions.

Lebanon’s economy “operates more than 60% on cash exchanges, the circulation of which the state cannot trace,” Daher said. “It is thanks to the segment of this cash in circulation that Hezbollah smuggles into Lebanon that it finances its activities and pays its employees and helps its popular base, alongside other sources of funding, both licit and illicit.”
However, the U.S. under President Donald Trump’s administration is placing renewed pressure on Lebanon’s new government to crack down on Hezbollah’s illicit activities.
New government crackdowns
In an apparent blow to Hezbollah’s funding operations, Lebanon’s central bank, the Banque Du Liban (BDL), issued a directive banning all financial institutions in the country from any dealings with Al-Qard al-Hasan — a Hezbollah-linked financial entity that provides local loans by taking gold and jewelry as collateral. It’s a tool by which Hezbollah cements support from the country’s Shiite population and gets more funding for its operations. Israel has specifically targeted Al-Qard al-Hasan facilities with airstrikes in the last year.
The BDL move was “ingenious,” said Matthew Levitt, a senior fellow at The Washington Institute and director of its counterterrorism and intelligence program, because Al-Qard al-Hasan has long been registered as a charity and thus was able to operate outside the Lebanese financial system, evading regulatory oversight.
“Here, the BDL appears to have found a way to jump the gap and say, ‘whatever you are, people can’t provide services for you. You can’t bank, and anybody who does is violating the law,” Levitt said.
Black smoke rises above the Dahieh neighborhood after Israeli airstrikes on targets of Lebanese Hezbollah, widely believed to be the last of a series of strikes aimed at Hashem Safieddine, the likely successor of the assassinated previous Hezbollah leader Hassan Nasrallah, who Israel announced has now been killed, near the southeast corner of the international airport on October 8, 2024 in Beirut, Lebanon.
Scott Peterson | Getty Images
Until recently, Hezbollah controlled almost all ports of entry in Lebanon, including the Beirut airport. Following Israel’s assault on the group, its airport is now under the control of the Lebanese government, which has fired staff linked to Hezbollah, detained smugglers, and implemented new surveillance technology.
And while Tehran is still funding its proxy group, its transport routes to Lebanon are dramatically restricted after losing a key ally with the fall of the Bashar al Assad regime in Syria. Flights coming in from Iran and other locations meant to bring in material support for Hezbollah are being heavily inspected, experts told CNBC.
“Cash transfers from abroad have been intercepted at the airport and border. We are talking about millions of dollars,” Daher said of the renewed security in the country.
‘The window of opportunity is now’
Many who want to see Hezbollah’s power dismantled say the time is now.
“When you now have Iran under tremendous stress, and Lebanon overtly trying to crack down on Hezbollah’s ability to function as an independent militia – and trying to target the funding it needs to be able to do that – you have an interesting opportunity,” Levitt, who also served as deputy assistant secretary for intelligence and analysis at the U.S. Treasury Department, told CNBC in an interview.
For the first time in decades, both the prime minister and president of Lebanon are interested in asserting monopoly over the use of force in the country, he added.
“They’re interested in securing the much, much needed international aid that Lebanon needs to get out of the economic crisis, and they’re interested in not saying no to the Trump administration.”
But it’s not that easy. The group, long described as the most powerful non-state organization in the Middle East, is still loyally followed by hundreds of thousands of people who rely on it for social services and ideological leadership — and it remains well-armed.
Notably, no one is officially demanding Hezbollah disband or cease to exist entirely. Trump’s envoy to the region Tom Barrack recently demanded Hezbollah lay down its weapons, a proposition the group has rejected.
“Hezbollah’s not going to disarm because you ask them nicely,” Levitt said. “But we have to enable the government of Lebanon to do this, give them the capability to do it, and have their back when they do it.”
That requires a combination of carrots and sticks, former U.S. officials say – ironically, tools that have in many cases been weakened by the shrinking of U.S. government resources under the Trump administration.

Alexander Zerden, principal at Washington-based risk advisory firm Capitol Peak Strategies who formerly served at the U.S. Treasury Department’s Office of Terrorism and Financial Intelligence, outlined some of those potential approaches.
“On the offensive side, the U.S. can and will likely continue to target Hezbollah financial networks inside and outside of Lebanon. The U.S. will seek to deny Hezbollah access to Syria, including lucrative reconstruction contracts,” Zerden said.
“On the incentive side, direct tools are more limited with reductions in diplomacy and development capabilities,” he noted – one example of that being the gutting of USAID, which served as a powerful diplomatic vehicle. “However,” he added, “there appears to be space for the U.S. to support economic reforms.”
For Ronnie Chatah, a Lebanese political analyst and host of The Beirut Banyan podcast, what’s truly needed is international pressure that would push Iran to relinquish its involvement in Lebanon.
“What has not yet shifted in Lebanon’s favor is the international aspect, meaning finding a way for Iran to abandon Lebanon that I think can only happen by strategic diplomacy,” said Chatah, whose father, a former Lebanese finance minister, was killed in a suspected Hezbollah assassination plot.
“If the Trump administration wants peace the way it says repeatedly, if Donald Trump wants the Nobel Peace Prize too, there has to be some way forward for Lebanon to take the spotlight and to find a peaceful resolution that in some ways satisfies Iran’s terms,” he told CNBC from Beirut.
What’s been done so far by both the U.S. and Lebanese governments is important, but will not ultimately break Hezbollah’s power in the country, Chatah warned.
“The window of opportunity is now. It’s not tomorrow, and unfortunately, it’s a closing window,” he said. “The intent is not enough. Whether it’s by the Trump administration or even whether it’s by the Lebanese president, the intention is not enough.”


Dario Amodei’s Call to Pace the AI Frontier and Its Market Ripple Effects

Rising Oil Prices And Persistent Inflation Complicate Fed Decision

Bridging the AI Skills Gap: How Gen Z Youth Demographics Are Transforming the Workforce

Armanino adds Strategic Accounting Outsourced Solutions

New 2023 K-1 instructions stir the CAMT pot for partnerships and corporations

Tax Strategy: Employee Retention Credit update
-
 Stock News1 week ago
S&P 500 September Outlook: Tech Rally Holds Index at 7,600
-
 Finance1 week ago
S&P 500 Outperforms Amid Strong Corporate Earnings as Treasury Yields Cap Equity Multiples
-
 Accounting1 week ago
Mandatory ESG Reporting Standards Demand Standardized Non-Financial Audit Trails
-
 Insights1 week ago
Climate Resilience and Offshore Wind and Land Restoration Milestones
-
 Leaders1 week ago
India Unveils ‘Saptadhara’ Reform Agenda Targeting Technology, Youth Skilling, and Growth
-
 Economics1 week ago
U.S. Inflation Outlook for 2027
-

 Economics5 days ago
Economic Profile of the superpower of western Europe
-
 Economics5 days ago
Sovereign Bond Yield Volatility and Inflationary Shocks Challenge Global Central Banks