The U.S. gross national debt crossed $40 trillion for the first time this week, according to Treasury Department data reported by NPR on August 20, 2026. The milestone caps a period of rapid fiscal expansion: the debt has doubled since 2017, and the federal government now spends more than $1 trillion a year just servicing interest on what it owes.
Why the Debt Load Is Accelerating
The debt has not grown at a steady pace. Instead, a combination of pandemic-era spending, tax policy changes, and elevated interest rates has compounded the federal government’s borrowing costs. As older Treasury bonds issued at lower rates mature, they are being refinanced at today’s higher prevailing rates, which pushes up the government’s annual interest bill even without any new borrowing.
That interest bill is no longer a minor line item. At more than $1 trillion annually, debt servicing now competes directly with discretionary spending on defense, infrastructure, and social programs. Economists watching the trend note that this dynamic can become self-reinforcing: higher interest costs widen the deficit, which requires more borrowing, which in turn raises future interest costs.
Bond Market Reaction
The debt milestone arrived during a volatile week for Treasury bonds. Bond prices fell even as equity markets touched record highs, a divergence that market analysts describe as bond investors signaling concern about the sustainability of federal borrowing, even as stock investors remain focused on corporate earnings and AI-driven growth.
U.S. Treasury Secretary Scott Bessent responded to the bond market pressure by expanding the Treasury’s debt buyback program, telling CNBC the size of buyback operations had been doubled to at least $4 billion per operation, with room to increase further. Buybacks are intended to support demand for existing Treasury securities and help stabilize yields during periods of market stress.
What Rising Debt Means for Ordinary Households
For everyday consumers, the national debt level itself is abstract, but its downstream effects are not. Elevated Treasury yields tend to push up borrowing costs across the economy, including mortgage rates, auto loans, and business credit. The same week the $40 trillion milestone was confirmed, average 30-year mortgage rates moved sharply, illustrating how bond market volatility connects directly to household borrowing costs.
Rising federal interest costs also narrow the government’s fiscal flexibility. As a larger share of the federal budget goes toward servicing debt rather than funding programs, policymakers face growing pressure to either cut spending, raise revenue, or both — choices that carry direct economic consequences for households and businesses alike.
What to Watch Next
The debt trajectory is expected to remain a central topic at the Federal Reserve’s Jackson Hole Economic Symposium, scheduled for August 27–29, 2026 — the first such gathering under new Fed Chair Kevin Warsh, who was confirmed by the Senate in a 54-45 vote in May 2026. While the symposium’s stated theme is financial innovation and payments policy, fiscal sustainability and its interaction with monetary policy are likely to feature in sideline discussions given the scale of the debt milestone.
Investors and households should watch upcoming Treasury auction results and any further changes to the buyback program as early indicators of how markets are digesting the government’s borrowing needs. A weak auction — one that requires higher yields to attract sufficient buyers — would be a signal that investor appetite for U.S. debt is softening further.
The $40 trillion figure is a threshold, not a crisis in itself. But combined with a bond market already showing signs of strain, it adds urgency to a fiscal conversation that has largely been deferred by successive Congresses and administrations.
The U.S. inflation outlook has become more uncertain as September 2026 begins with a combination of elevated consumer prices, rising producer costs and a renewed surge in energy prices. Crude oil has moved above $100 per barrel amid heightened geopolitical and supply concerns, while the national average gasoline price has also moved decisively above $4 per gallon. AAA reported that the national average price of regular gasoline reached $4.27 on September 10, up 13 cents in one week, and its latest data showed an average of approximately $4.31 per gallon on September 12.
These developments create a potentially significant inflationary challenge for households, businesses and the Federal Reserve. The immediate concern is that higher energy prices could reverse some of the progress made toward reducing inflation. More importantly, persistent energy costs could spread beyond gasoline into transportation, manufacturing, logistics, food distribution and other business expenses. This makes the September 16, 2026 Federal Open Market Committee decision particularly important for financial markets and the broader U.S. economy.
August CPI Shows Inflation Remains Sticky
The latest Consumer Price Index provides evidence that inflationary pressure remains stronger than the Federal Reserve would prefer. According to the U.S. Bureau of Labor Statistics, the CPI increased 0.4% in August 2026, following a 0.1% increase in July. On a 12-month basis, consumer prices were up 3.4%, meaning inflation remained substantially above the Federal Reserve’s 2% longer-run objective. The details of the report are particularly important because gasoline prices increased 3.9% during August and accounted for more than one-third of the monthly increase in the overall CPI.
The broader energy index increased 2.1% during the month and was up 16.3% over the previous year. At the same time, core CPI, which excludes food and energy, increased 0.3% in August and was 2.4% higher than a year earlier. This indicates that inflation is not exclusively an energy problem. Underlying price pressures remain present even before accounting for the latest September oil-price escalation.
PPI Signals Continuing Producer-Cost Pressure
The Producer Price Index adds another warning signal to the inflation picture. The BLS reported that the PPI for final demand increased 0.4% in August, while final-demand prices were up 5.4% from a year earlier. Final-demand goods prices increased 1.1%, while final-demand services rose 0.1%. Energy was a major contributor to the increase, with final-demand energy prices rising 4.2%.
Diesel fuel prices alone jumped 24.1% during August and accounted for more than one-third of the increase in final-demand goods. These figures matter because producer prices can eventually influence consumer prices when businesses pass higher input costs to customers. The PPI therefore provides an important warning that inflationary pressure may not disappear quickly.
Oil Above $100 Creates a New Inflation Risk
The September oil-price surge represents the most significant new variable for the inflation outlook. Brent crude has moved above $100 per barrel as geopolitical tensions and disruptions affecting Middle Eastern energy supplies have intensified. Reuters reported that oil prices rose sharply as renewed attacks and concerns surrounding regional energy infrastructure and shipping increased fears of prolonged supply disruptions. Higher crude prices can affect the economy through several channels. Gasoline prices respond relatively quickly, directly increasing household transportation expenses. Diesel prices are equally important because trucking, agriculture, construction and freight transportation depend heavily on diesel fuel. Businesses facing higher transportation and energy costs may eventually pass some of those expenses to consumers. If the oil shock persists, therefore, the inflation impact could extend well beyond the energy category.
The September FOMC Meeting Takes Center Stage
The Federal Reserve’s September meeting is scheduled for September 15–16, 2026, with the policy decision and press conference on September 16. The latest inflation data have increased the pressure on policymakers to demonstrate that they remain committed to controlling inflation. Financial markets are increasingly anticipating a rate increase, with Reuters reporting that expectations for a hike strengthened following the August CPI report and rising oil prices. However, a rate hike should not be treated as certain until the FOMC actually announces its decision. The central challenge for policymakers is that monetary policy cannot directly increase global oil supply or lower gasoline prices. Raising interest rates can, however, reduce demand and help prevent a temporary energy shock from becoming embedded in wages, services prices and inflation expectations.
A Potential Policy Dilemma for the Fed
The Federal Reserve therefore faces a difficult policy trade-off. If it raises interest rates to counter persistent inflation, borrowing costs for mortgages, businesses, consumers and investors could remain elevated for longer. That could slow economic growth at a time when higher energy prices are already reducing household purchasing power. On the other hand, failing to respond to persistent inflation could allow inflation expectations to become less firmly anchored. The distinction between a temporary supply shock and persistent inflation will be central to the Fed’s decision. If oil prices retreat quickly, policymakers could reasonably view much of the energy increase as temporary. If crude remains above $100 for an extended period, the risk of broader inflation becomes considerably greater.
Implications for the 2027 Inflation Outlook
The September developments suggest that the U.S. inflation outlook for 2027 is now more uncertain than earlier forecasts indicated. The Federal Reserve and other institutions have previously expected inflation to move toward the 2% area, but those projections depend on assumptions about energy prices, domestic demand and the persistence of underlying inflation. A prolonged oil shock could delay the return to target by increasing transportation and production costs throughout the economy. Businesses could respond by raising prices, while consumers could reduce discretionary spending because more income is being devoted to gasoline, heating and transportation. The result could be an uncomfortable combination of higher inflation and slower economic growth. Such an environment would make monetary policy significantly more difficult.
Conclusion
The latest data present a clear warning that the U.S. inflation fight is not over. August CPI increased 0.4%, core CPI rose 0.3%, and headline inflation remained at 3.4% year over year. August PPI also increased 0.4%, with energy prices and diesel fuel making particularly large contributions to producer-cost growth. Meanwhile, gasoline prices have moved above $4 per gallon nationally, and oil prices have crossed the $100-per-barrel threshold.
These developments increase the probability that the Federal Reserve will maintain a hawkish posture at its September 15–16 meeting and could support a rate increase, although the decision remains dependent on the Committee’s assessment of the complete economic data. The central question for the remainder of 2026 is whether the energy shock remains temporary or develops into a broader inflationary cycle. If oil remains elevated, the consequences could extend into 2027 through higher transportation, production and consumer costs. For investors, businesses and households, energy prices and the Federal Reserve’s policy response will therefore be two of the most important economic variables to monitor through the remainder of 2026.
Global financial markets are confronting renewed instability as major sovereign bond yields spike across the United States, Europe, and Asia. Central banks face a challenging operational environment driven by recurring supply-side inflation shocks, geopolitical friction in energy transport corridors, and extreme climate events disrupting global agricultural supply chains. Economists increasingly argue that these structural headwinds may force benchmark interest rates to remain higher for longer than previously anticipated.
Long-duration government yields experienced heightened volatility
Throughout the current week, long-duration government yields experienced heightened volatility. In the United States, 30-year Treasury yields touched levels not seen since the 2008 financial crisis before stabilizing slightly. The sell-off in sovereign debt underscores growing market concern that central banks will be constrained in their ability to ease monetary policy. Despite moderating wage growth, sticky service-sector inflation and surging energy prices—with global crude oil benchmarks fluctuating near $90 a barrel—are keeping inflation metrics elevated.
Emergence of recurring structural shocks
A critical factor driving this bond market shift is the emergence of recurring structural shocks. Economists highlight that supply chain disruptions from extreme weather and geopolitical realignments create persistent upward pressure on input costs. Unlike demand-driven inflation, which central banks can counter through interest rate hikes, supply-side shocks reduce economic capacity while simultaneously driving up consumer prices, raising the threat of stagflationary pressures.
Emphasize data-dependent policy frameworks
In response, international monetary authorities are emphasizing data-dependent policy frameworks. Central bank leaders caution that prematurely lowering interest rates risks unanchoring long-term inflation expectations. Financial institutions, sovereign wealth funds, and institutional asset managers are adjusting their asset allocation models, favoring shorter-duration fixed income assets and inflation-protected securities to cushion against bond market volatility.
Why This Information Matters
Fluctuations in global sovereign bond yields directly determine the cost of debt across the economy, influencing everything from enterprise credit spreads to consumer loan rates. Understanding these macroeconomic dynamics allows corporate CFOs, institutional investors, and business planners to manage capital allocations, hedge currency and rate risks, and prepare for prolonged periods of elevated borrowing costs.
Structural Dynamics, Macroeconomic Performance, and Future Trajectory
Germany
Germany maintains its standing as the world’s third-largest national economy, trailing only the United States and China. According to macroeconomic data and structural analyses from the International Monetary Fund (IMF World Economic Outlook), Germany remains the fundamental cornerstone of the European single market. The nation’s economic identity is anchored by high-value industrial engineering, advanced manufacturing capabilities, and a highly specialized, productive labor force. However, as detailed across primary macroeconomic assessments, the country is navigating a crucial period of structural realignment. This ongoing economic evolution is characterized by modest baseline real GDP growth, persistent energy cost recalibrations following geopolitical shifts across Central Europe, and demographically driven labor market constraints.
Macroeconomic Profile and Baseline IMF Indicators
Germany’s overall economic framework demonstrates an exceptional baseline of nominal wealth and capital intensity, even as annual real rate expansion moderates. Based on official macroeconomic projections compiled within the International Monetary Fund’s World Economic Outlook documentation, the structural indicators defining Germany’s global position highlight both resilience and maturing output trends.
The country’s projected nominal Gross Domestic Product (GDP) is on track to reach $5.64 trillion by 2027. This immense volume solidifies Germany’s position as Europe’s undisputed economic powerhouse and the third-largest economy globally, maintaining a substantial cushion over peer developed nations in the European Union. This top-tier ranking reflects decades of industrial accumulation, highly integrated regional supply chains, and extensive export footprints in global capital goods markets.
In tandem with its absolute output volume, Germany achieves a projected GDP per capita of $67,613. Across a population base of approximately 83 million residents, this elevated per capita figure underscores a remarkably high standard of living, deep social safety net provisions, and significant capital intensity per worker. German manufacturing productivity remains a key catalyst, allowing high real wages to coexist with export competitiveness in specialized global market segments.
However, when evaluating real volume expansion, Germany’s projected real GDP growth rate centers near 1.18% annually. Cyclical output fluctuations within recent reporting periods generally range between 0.8% and 1.3%, signaling a transition toward a slower, mature baseline growth trajectory. Compared to the rapid, demographic-fueled growth rates seen across emerging Asian economies, Germany’s trajectory reflects the structural realities of an advanced, fully industrialized economy operating near the technological frontier.
Core Performing Economic and Industrial Sectors
The backbone of Germany’s macroeconomy is concentrated in specialized manufacturing industries, cutting-edge technology, and high-value service sectors. This complex industrial ecosystem—often driven by large multinational corporations alongside the Mittelstand (small-to-medium enterprise sector)—continues to drive national value added.
1. Automotive Engineering and Advanced Mobility
Germany’s automotive sector remains a global benchmark for engineering excellence and industrial prestige. German carmakers and tier-one component suppliers account for a major share of total manufacturing exports. The sector is currently navigating an unprecedented capital transformation, reallocating billions of euros toward electric vehicle architectures, battery cell chemical research, and autonomous driving software. While international market competition in the electric vehicle segment has intensified, German automotive brands maintain powerful global market equity and superior premium-segment margins.
2. Industrial Machinery, Robotics, and Automation
Renowned worldwide for precision, durability, and technological integration, Germany’s industrial machinery sector is a primary capital goods supplier to factories across Europe, North America, and East Asia. From heavy industrial presses and laser cutting equipment to advanced industrial robotics, German engineering firms deliver the tools required for modern global manufacturing. This industry benefits directly from global trends toward automation, smart factory upgrades, and supply chain digitalization.
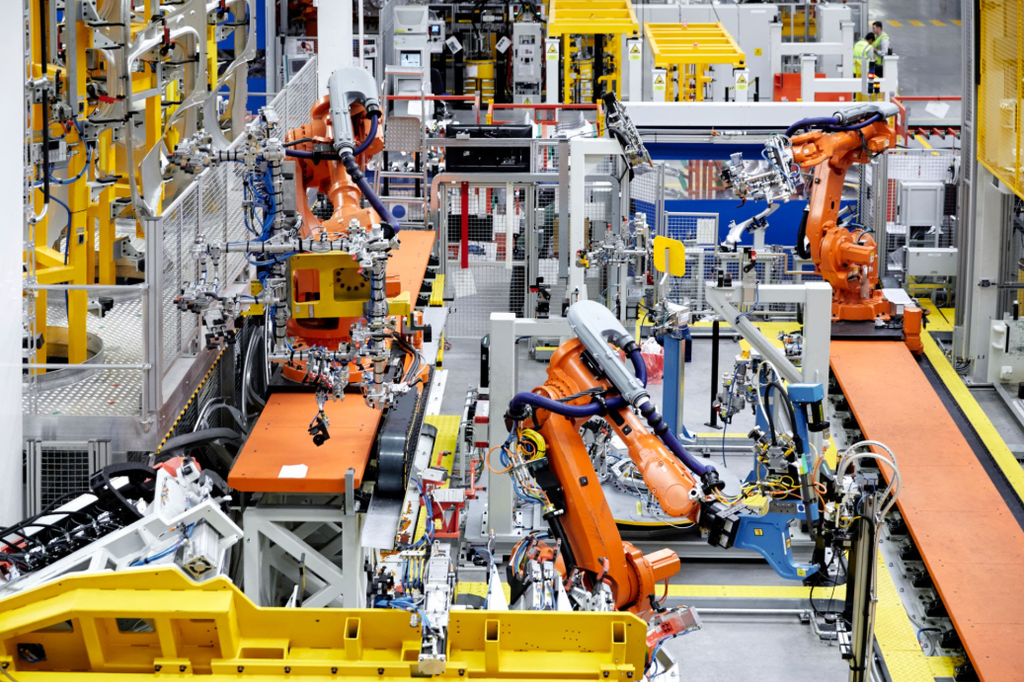
Automated robotics in a German manufacturing plant
3. Chemicals, Materials, and Pharmaceuticals
The domestic chemical industry serves as an essential foundational input supplier for nearly every downstream European manufacturing activity. German chemical conglomerates produce high-performance polymers, specialty synthetic compounds, industrial gases, and agricultural inputs. Simultaneously, the pharmaceutical and biotechnology segment continues to generate high-margin export earnings, supported by world-class research facilities and heavy private sector research and development spending.
4. Clean Energy Technology and Digital Infrastructure
In response to changing geopolitical realities and climate policy mandates, public and private capital flows are increasingly directed toward the clean energy transition. Germany is aggressively expanding its renewable energy capacity, focusing on offshore wind generation, utility-scale solar installations, and green hydrogen transmission networks. At the same time, private enterprise and state funding are modernizing digital infrastructure, enhancing logistics networks, financial services, and administrative productivity.
Structural Headwinds and Growth Dynamics
While Germany maintains exceptional capital efficiency and industrial depth, the IMF World Economic Outlook documentation identifies critical structural challenges that hinder near-term output expansion.
A fundamental challenge centers on the recalibration of industrial energy costs. Geopolitical shifts across Central Europe necessitated a rapid divergence from historically cheap pipeline natural gas. Transitioning to sea-borne liquefied natural gas (LNG) imports and accelerated renewable integration required substantial capital expenditure, temporarily elevating baseline operational costs for energy-intensive manufacturing segments. While prices have stabilized relative to initial shock periods, structural energy costs remain higher than those enjoyed by competitors in North America, pressing German firms to continuously innovate in energy efficiency.
Furthermore, demographic aging represents a persistent long-term constraint on output growth. As the post-war generation retires, the domestic labor market faces a shrinking workforce, creating acute skill shortages across industrial trade, engineering, healthcare, and technology sectors. This demographic trend increases dependency ratios, places fiscal demands on social security systems, and limits the potential growth rate of national production unless offset by rapid productivity gains.
Additionally, evolving global fiscal priorities play an increasingly prominent role in Germany’s macroeconomic outlook. In line with broader regional shifts analyzed in the April 2026 IMF report—specifically regarding defense spending and macroeconomic trade-offs—Germany and its NATO allies are scaling up national security expenditures. While increased defense procurement acts as a targeted fiscal stimulus for domestic high-tech manufacturing, defense electronics, and heavy equipment, policymakers face the complex task of balancing these long-term commitments against strict constitutional debt rules and required civilian infrastructure spending.
Global Trade and Regional Integration
Germany’s macroeconomic resilience relies heavily on its deep integration within the European Union’s single market. Duty-free access across EU member nations guarantees reliable consumer and industrial demand for German equipment, vehicles, and high-value chemicals. Furthermore, German multinational conglomerates generate vast net primary income from foreign direct investments globally. Combined with strong exports of specialized high-tech services, Germany routinely maintains a surplus current account balance, providing a crucial stabilizing cushion against broader international financial volatility.
Strategic Policy Outlook
To lift its medium-term real GDP growth beyond the present ~1.2% baseline projection, national policy initiatives must focus on structural modernization. Key priority areas include streamlining administrative and environmental permitting processes for energy and digital infrastructure, creating clearer immigration pathways for high-skilled international workers to counteract demographic headwinds, and deploying targeted tax incentives for private sector research and green technology adoption. Through these concerted structural adjustments, Germany is well-positioned to preserve its preeminent standing as Europe’s premier industrial power and an anchor of global economic stability.