Finance
Unraveling the legal, economic and market ramifications if Trump tries to fire Fed Chair Powell

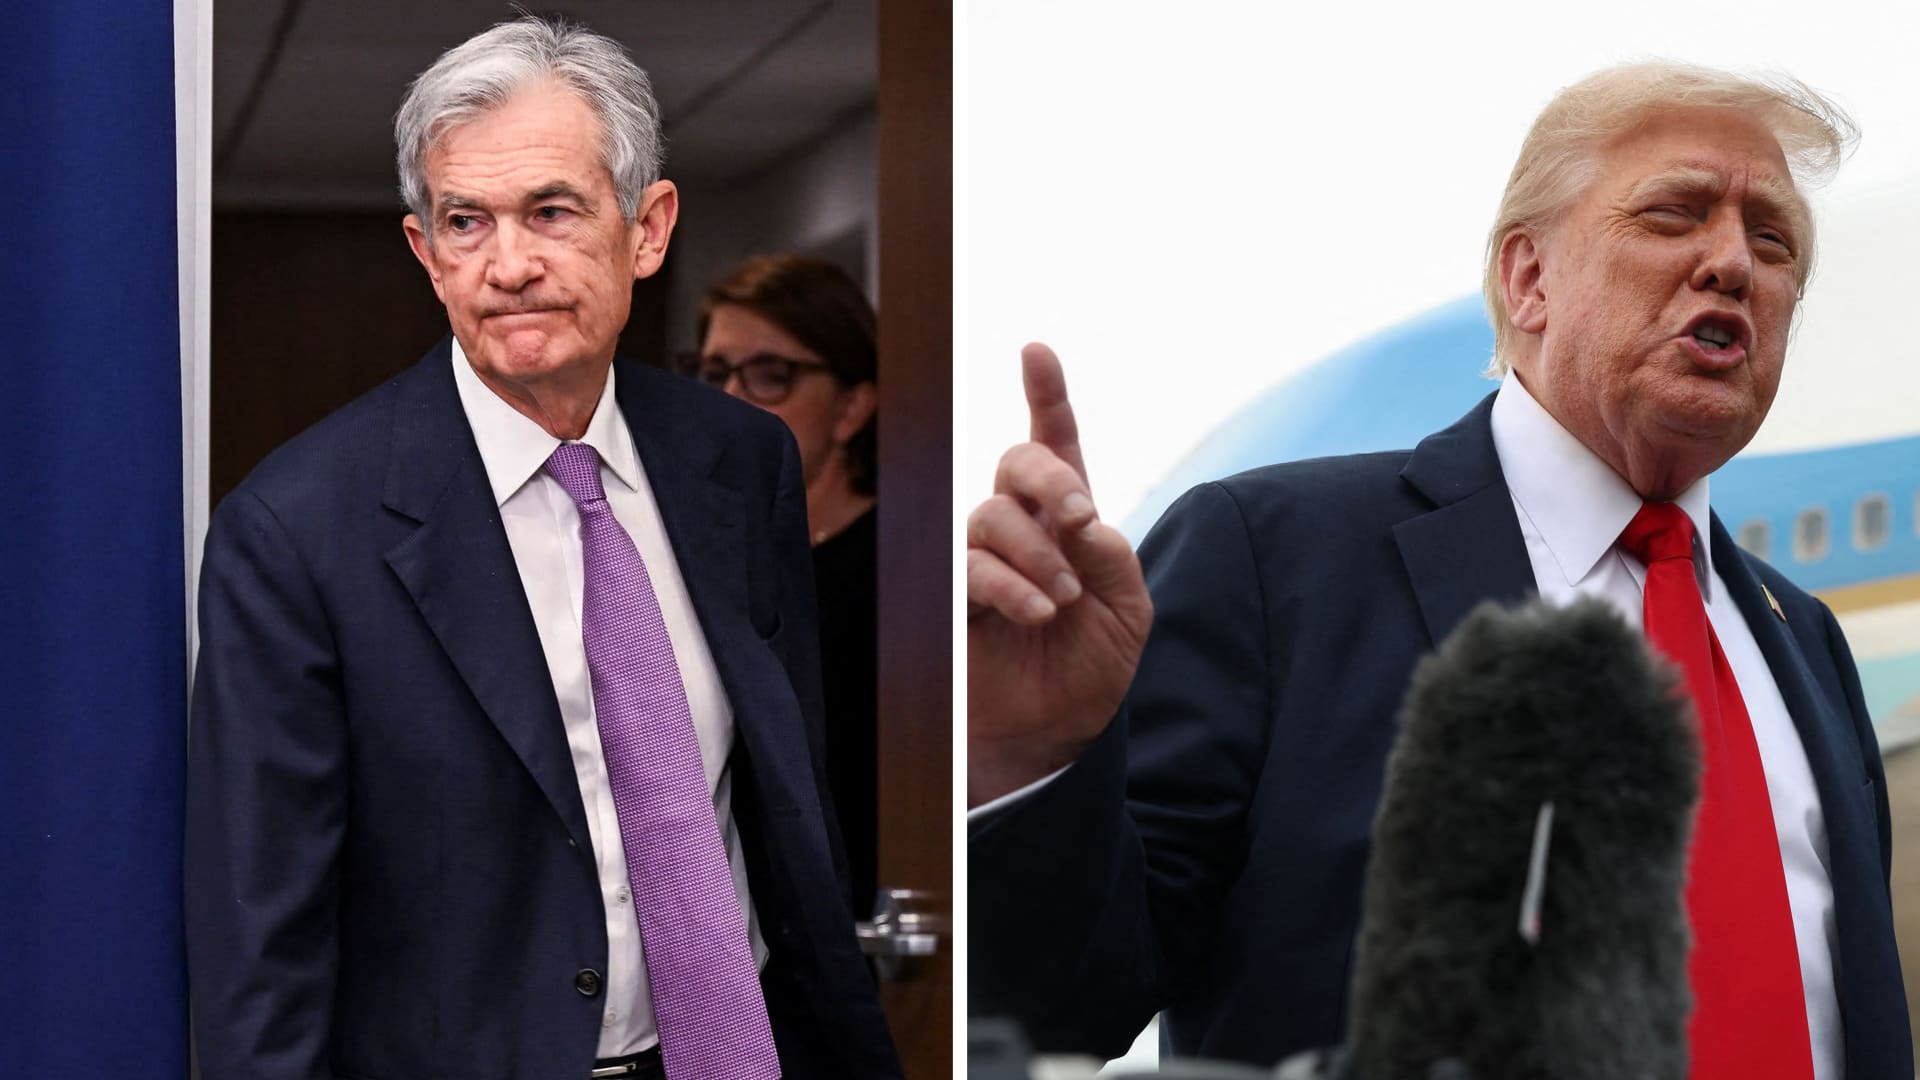
U.S. Federal Reserve Chair, Jerome Powell and U.S. President Donald Trump.
Annabelle Gordon | Kevin Lamarque | Reuters
If President Donald Trump tries to fire Federal Reserve Chair Jerome Powell, it would almost certainly set off a courtroom battle that legal and policy experts say is bound to get messy, with uncertain impacts on the central bank, financial markets and the economy.
The tempestuous situation poses a myriad of thorny questions for which there are no easy answers considering no president ever has tried to unseat a Fed chair.
Among them:
- Does Trump have the authority to remove Powell? The answer is almost certainly no, not without meeting the legal threshold of “cause.” However, that raises additional questions over what would constitute cause, with growing suspicion in Washington and Wall Street that the president is using criticism over the Fed’s building expansion as a pretext to establish that condition.
- What happens next from a legal standpoint? Most people familiar with the situation say Powell would sue if Trump tries dumping him. The case likely would head to the Supreme Court, which ruled recently that the quasi-governmental Fed is a special entity immune from arbitrary personnel moves regarding governors. But that didn’t address the issues surrounding cause.
- Beyond a lawsuit, what else could Powell do? If he gets fired as chair of the Board of Governors, the Federal Open Market Committee, which is the Fed body that sets interest rates, simply could retain Powell as chair, giving him continued influence over monetary policy. The FOMC chair historically has been the Fed board chair, but that’s not a requirement.
- Does Trump really want to fire Powell, or is he simply setting him up as a scapegoat should the economy go south? The president has shown himself to be a shrewd and often times calculating political player, and having Powell around as a punching bag could be useful as crucial mid-term elections approach.
“What is extraordinary here is the president going back and forth and discussing loudly whether he might fire or try to fire the Fed chair,” said Bill English, the Fed’s former director of monetary affairs and now a Yale professor. “Of course, we’ve never gone through that, so we don’t know legally how that would work and how the courts would see that and so on. So, I think it’s all things that we haven’t seen before, and raises real uncertainties.”
A rapid about-face
Even by Trump’s standards, the event surrounding Powell of late have been stunning.
After an extended campaign of ad hominem attacks on Powell and demands for lower interest rates, Trump met with Republican congressional members Tuesday evening and asked them if he should fire the Fed chair, according to a senior administration official.
After the GOP members showed their backing for the move, the president indicated to them he would move on Powell “soon,” the official said.
However, no sooner did news break of the meeting then Trump told reporters that he’s not considering a move, saying it’s “highly unlikely” while simultaneously wondering out loud whether alleged mismanagement of the $2.5 billion expansion might qualify as cause.
Subsequent reports suggested that Trump’s lawyers indicated that he would have a hard time legally dismissing Powell. The Supreme Court’s ruling in Trump v. Wilcox this year called the Fed a “uniquely structured, quasi-private entity” whose governors enjoy insulation from removal for political or policy reasons.
That, of course, does not mean that Trump won’t try.
“It’s a very high bar legally, but there also haven’t been really any historical precedents for it,” Jonathan Kanter, former assistant attorney general during the Biden administration, said on CNBC. “So it would get litigated in court, probably be quite a bit of a circus, but, yeah, the standard is very high. It has to be for cause, and it has to be for neglect, malfeasance, abuse.”

The legal fallout
Powell’s options would entail suing and asking for a stay on any Trump removal action, Kanter said. The tactic itself that could push resolution past the expiration of the Fed chair’s term in May 2026.
As it winds through the legal system, the case would draw close attention and either could act as a bulwark for Fed independence, or reduce the normally sacrosanct central bank to just another political body subject to the whims of the Oval Office.
“The Supreme Court has signaled it would likely side with the Fed chair,” Kanter said. “It views the Fed as historically different than other independent agencies. Then it would kick the case right back down to a district court, which would determine whether the president had a basis to fire the Fed chair.”
Despite seemingly low chances of success, going after Powell still could serve a political purpose for Trump.
“I think Trump is setting it up so that there’s a sword of Damocles hanging over Powell’s head throughout the rest of his tenure,” Kanter said. “If there is a sustained period of inflation or stagflation, Trump has the ability to say, well, it’s this guy’s fault because he didn’t lower interest rates.”
Indeed, the Trump-Powell dispute by all appearances runs deeper than qualms over the building renovations.
Quest for rate cuts
Trump wants sharply lower interest rates, and he wants them now, economic consequences be damned.
The president was on the attack again Friday, railing against Powell and his fellow central bankers. In a Truth Social post, Trump charged Powell and the FOMC officials are “choking out the housing market with their high rate, making it difficult for people, especially the young, to buy a house. He is truly one of my worst appointments.”
Up until recently, Trump has reserved most of his criticism for Powell individually. But on Friday, he also said, “the Fed Board has done nothing to stop this ‘numbskull’ from hurting so many people. In many ways the Board is equally to blame!” Finally, using his nickname for Powell, he said, “I can’t tell you how dumb Too Late is – So bad for our Country!”
Besides Powell, Trump has two appointees on the board dating back to his first term: governors Michelle Bowman and Christopher Waller, both of whom have said they are leaning toward a rate cut when the FOMC meets at the end of July.
Beyond those two, though, other members have not expressed any appetite for easing before the September meeting. There are 12 voters on the FOMC, and the chair is just one of them. Fed watchers including English, who served as the FOMC secretary, see policymakers pushed into a corner where cutting in July would seem like acquiescing to Trump’s demands.
That’s part of a larger concern on Wall Street over the reputational fallout the Fed faces as the Trump White House ramps up its efforts to use politics to influence monetary policy.
Market, economic fallout
“The experience of other countries in which governments have suppressed central bank independence has generally been a combination of a slippery slope and the occasional sudden drop,” Jonas Goltermann, deputy chief markets economists at Capital Economics, said in a recent note. “Unlike raising tariffs, which can be withdrawn before the real damage is done, the reputational costs from firing Powell would be harder to undo.”
Then there are the market and economic issues.
Firing Powell would be unlikely to change the committee’s approach to monetary policy, and in fact could harden its position on rates.
Even if the FOMC did cut, it could do more harm than good to Trump’s goal of lowering finance costs on the national debt. The last time the Fed cut, in the final four months of 2024, Treasury yields rose almost in perfect reverse correlation to the rate reductions, and the same thing could happen again if markets perceive the Fed is surrendering its inflation-fighting credentials to placate Trump.
“The historical record suggests that political interference contributed to poor monetary policy in the late ’60s and early ’70s, with unfavorable consequences for inflation developments,” JPMorgan Chase chief U.S. economist Michael Feroli wrote. “Any reduction in the independence of the Fed would likely add upside risks to an inflation outlook that is already subject to upward pressures from tariffs and somewhat elevated inflation expectations.”
While Trump wants the Fed to slash its key borrowing rate by 3 percentage points, such a move could raise inflation expectations, causing fixed income investors to demand higher yields, “thereby increasing longer-term interest rates, weighing on the outlook for economic activity, and worsening the fiscal position,” Feroli added.
For the time being, Powell and Co. is expected to continue to conduct business and make decisions based on data, with the constant drumbeat of Trump serving as a distraction that doesn’t seem like it will go away, even if the president ultimately never tries to fire the Fed chief.
“Well, it isn’t helpful to have the president be so aggressively antagonistic trying to pressure the Fed. It’s not unprecedented that a president has views on monetary policy. We’ve seen that over time. But I think what’s different about this time is that it’s been pretty persistent and unrelenting,” former Cleveland Fed President Loretta Mester said Friday on CNBC. “That will not change how the Fed makes it goes about making its decisions on monetary policy.”



Dario Amodei’s Call to Pace the AI Frontier and Its Market Ripple Effects

Rising Oil Prices And Persistent Inflation Complicate Fed Decision

Bridging the AI Skills Gap: How Gen Z Youth Demographics Are Transforming the Workforce

Armanino adds Strategic Accounting Outsourced Solutions

New 2023 K-1 instructions stir the CAMT pot for partnerships and corporations

Tax Strategy: Employee Retention Credit update
-
 Stock News1 week ago
S&P 500 September Outlook: Tech Rally Holds Index at 7,600
-
 Finance1 week ago
S&P 500 Outperforms Amid Strong Corporate Earnings as Treasury Yields Cap Equity Multiples
-
 Leaders1 week ago
India Unveils ‘Saptadhara’ Reform Agenda Targeting Technology, Youth Skilling, and Growth
-
 Economics1 week ago
U.S. Inflation Outlook for 2027
-

 Economics5 days ago
Economic Profile of the superpower of western Europe
-
 Economics5 days ago
Sovereign Bond Yield Volatility and Inflationary Shocks Challenge Global Central Banks
-
 Finance5 days ago
Big Tech Enterprise Borrowing Reaches $135 Billion as Hyperscalers Fund AI Infrastructure
-
 Economics2 days ago
Rising Oil Prices And Persistent Inflation Complicate Fed Decision