One of the most powerful things an accounting firm leader can do is to reveal their human side, according to experts at this year’s Bridging the Gap Conference — whether that means revealing their own vulnerability and weaknesses, admitting a mistake, or working to connect more deeply with employees and fellow partners.
For Randy Crabtree, that meant acknowledging that he needed help in the wake of a stroke, and then having the courage to reimagine his career and firm.
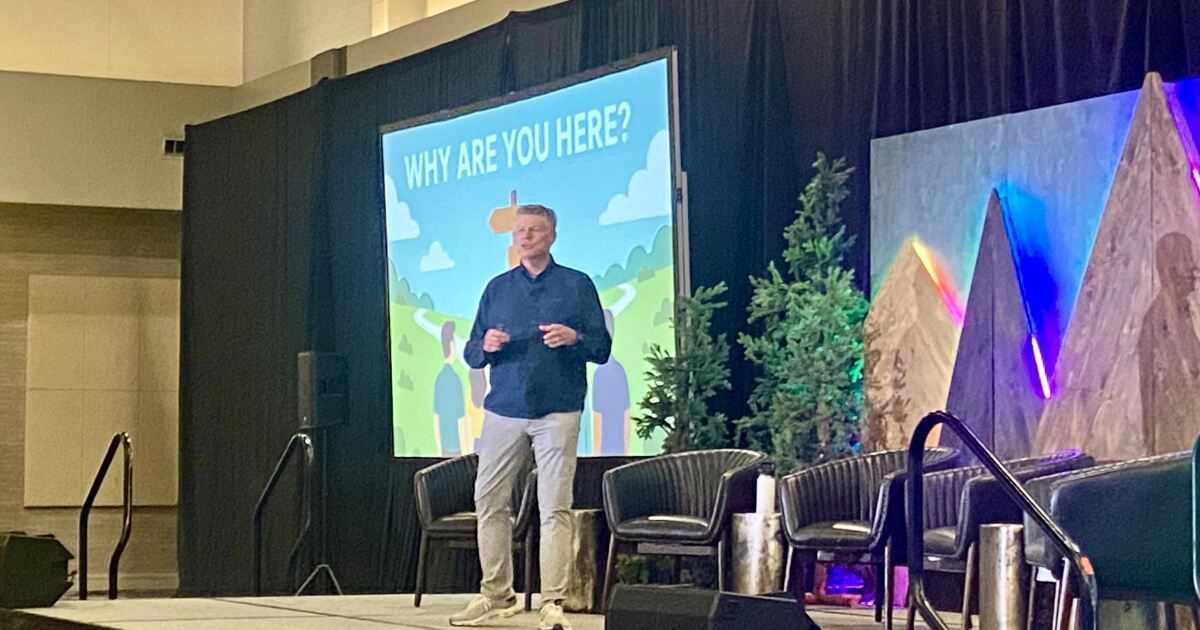
In his opening keynote, “The Power of Vulnerability: Letting Go to Find What Matters Most,” at the 2025 BTG Conference, being held this week in Denver, Crabtree recounted his harrowing experience of suffering two strokes in quick succession in 2014, and the spiral of depression and mental health issues that followed, which he tried to manage on his own.
“I said, ‘I can fix this; I’m a CPA — this is what I do. I fix things.’ For the next two years, I left it up to me,” he said. “Bad decision.”
Randy Crabtree at the 2025 Bridging the Gap Conference
His depression refused to lift, an attempt at therapy failed because he refused to acknowledge that there were things outside of his control, and his dark thoughts got darker and darker until he had no choice but to open up.
“Finally, I decided it’s time to be vulnerable, to admit that I can’t do this by myself,” Crabtree said.
He found a second therapist, and with their help, “I took control of my thinking; I took control of my future; I took back my life.”
Paradoxically, vulnerability had given him back control — but it also opened up a whole set of questions about his professional career, including his role as managing partner of Tri-Merit Specialty Tax Services (a tax advisory firm that also hosts Bridging the Gap).
“I started thinking, ‘What have I been doing with my whole life? Have I been taking the wrong path all my life?'” he asked. “I looked at what I’d been doing at Tri-Merit. I looked at it and said, ‘Am I a managing partner? Is this who I’m supposed to be? Is this my passion and my skills? No.'”
His passion in life had always been entrepreneurial, not managerial — starting companies, not running them — and he decided he needed to make a change.
“I had to go to everyone and say, ‘I’m not equipped for this role. I’m not going to help us in the future if I continue doing what I’m doing,'” he explained. “It was a vulnerable leadership moment — and it opened up opportunities.”
His co-founder took over Crabtree’s role as managing partner — “and he was built for being an MP. I hadn’t known that. I realized I needed to know more about people.”
It turned out it wasn’t just his co-founder who was ready for a new role: “It was the entire firm — lots of people were able to move to new and different roles,” he said.
And with so many of his colleagues benefiting from being able to take on new roles, Crabtree began building a new role for himself, as a champion of mental health in the accounting profession. He featured it prominently on his podcast, and began presenting sessions on mental health and burnout across the country, including one in early 2023 at a firm in California, at the end of which the firm’s managing partner came up on stage and opened up about his own family’s struggles with depression.
“I could feel the change in the room,” Crabtree recalled, as the openness of their leadership modelled a new way of thinking for the staff.
A few months later he got a call from that managing partner, who had only recently suffered a stroke himself, and wanted to thank Crabtree for sharing his own story in a way that helped the managing partner get through his own issues.
When the call was over, Crabtree got his marketing team together and began laying the groundwork for Bridging the Gap, which places a strong emphasis on issues of mental health, burnout — and modelling a better kind of accounting firm for future generations.
A shared humanity
One key element of that better kind of firm is treating employees as individuals — not just because it’s the decent thing to do (though it is), but because it can also play a huge role in retention and creating a workplace where people can do their best work.
And vulnerability and openness on the part of leadership can play a major role here, too, as Shea Keats and Michelle Rose — the CEO and COO, respectively, of Breakaway Advising — shared in a session on “The Proper Care and Feeding of Accountants.”
They strongly advocated getting to know prospective and current employees much better through a framework of multiple questions about everything from their favorite show and their favorite place to shop, to the names and titles of the people closest to them, and even “How will I know when you’re mad?”
“The first step for getting good responses is to do it yourself,” explained Rose. “Answer these questions and share them with your people.”
The goal is to come away with a host of personal knowledge about your employees that allow you to shape your relationships with them in ways that make them feel seen and appreciated as individuals — as well as to keep from unintentionally killing them.
“How many times have we found out too late that someone has a hazelnut allergy?” Rose asked. “Or that you sent a microbrew kit to someone who was struggling with alcohol?”
“Knowing these things is so simple and silly, but it makes a big difference,” said Keats.
Sharing information about yourself to make staff feel comfortable sharing is useful, but so is sharing your mistakes.
“It’s important to model openness,” said Keats. “Recently, our chief of staff missed five things because issues came up with her kids, and that was fine — she shared with the team why she missed the deadlines and why it was OK because they would be taken care of, and we responded to show that it was OK, to model that for our younger employees.”
In the end, this kind of openness will take firms to the next level as workplaces of choice. “We talk a lot about the Platinum Rule,” Keats explained. “We all know the Golden Rule — ‘Treat others how you want to be treated’ — but the Platinum Rule is about treating people how they want to be treated.”
“This is how you retain your team over time,” she said.
The accounting and audit landscape in 2026 is defined by the full integration of artificial intelligence directly into core enterprise software platforms. Rather than operating as standalone third-party tools, generative AI, automated reconciliation, and continuous anomaly detection are now natively embedded within major ERP engines including SAP, Oracle, Microsoft Dynamics, QuickBooks, and Sage. This technology integration is transforming daily financial operations, internal reporting controls, and external audit workflows.
Recent industry benchmark surveys reveal a widening performance gap
Recent industry benchmark surveys reveal a widening performance gap between finance teams utilizing integrated AI automation and those relying on legacy manual processes. Organizations actively leveraging embedded AI report up to 37% higher revenue per employee, driven by automated invoice matching, instant ledger entries, and predictive cash flow modeling. Routine, high-volume transactional tasks that once required manual intervention are now executed in real time with continuous digital audit trails.
AI introduces new governance and control responsibilities
However, the widespread deployment of embedded AI introduces new governance and control responsibilities for accounting professionals. Auditing standards now mandate strict verification protocols for algorithmically generated journal entries and financial commentary. External auditors are evaluating enterprise AI governance frameworks, reviewing automated rule sets, testing data ingestion pipelines, and ensuring that financial controllers maintain human-in-the-loop oversight over automated system outputs.
Furthermore, cloud governance and data security have become core operational skills for modern CPAs and controllers. As financial ledgers and client data stream through interconnected cloud ecosystem APIs, accounting teams must implement multi-factor access controls, continuous data encryption, and strict data privacy compliance to protect sensitive financial records from cyber vulnerabilities.
The embedding of AI into enterprise accounting software redefines internal financial controls and career requirements for accounting professionals. Business owners and finance leaders must update governance protocols, invest in staff digital literacy, and ensure accounting systems maintain rigorous audit compliance to capture productivity gains safely.
Corporate accounting departments face an expanded regulatory mandate as mandatory sustainability and Environmental, Social, and Governance (ESG) reporting frameworks take full effect internationally. Governed by the European Union’s Corporate Sustainability Reporting Directive (CSRD) and the International Sustainability Standards Board (ISSB) IFRS S1 and S2 standards, enterprise financial controllers are now legally required to track, verify, and report non-financial data with the same internal controls and auditability as traditional financial statements.
The expansion shifts ESG compliance
This regulatory expansion shifts ESG compliance from marketing departments to corporate accounting offices. Financial managers are now responsible for gathering, consolidating, and verifying carbon emissions metrics, supply chain labor conditions, water usage, and climate risk exposures across multi-tiered corporate structures. These non-financial metrics must be integrated into standardized general ledgers to withstand rigorous third-party audit assurance processes.
To comply with these rigorous reporting mandates, accounting software providers have added dedicated ESG modules designed to aggregate data from IoT sensors, utility platforms, and vendor management systems. Controllers are implementing internal control frameworks—modeled after traditional COSO frameworks—to ensure the completeness, accuracy, and consistency of sustainability disclosures, protecting organizations against greenwashing penalties and litigation risks.
The transition requires significant cross-functional collaboration between accounting teams, legal counsel, and operational directors. Accounting professionals are expanding their technical expertise beyond financial ledgers to master carbon accounting methodologies, lifecycle assessment standards, and non-financial data governance protocols, fundamentally expanding the role of the modern corporate accountant.
Why This Information Matters
Mandatory ESG disclosures require companies to treat environmental and social metrics as audited financial records. Executives, accountants, and board members must institute formal tracking and assurance processes to satisfy legal mandates, maintain investor confidence, and mitigate regulatory non-compliance risks.
A proposal from the U.S. Securities and Exchange Commission to potentially shift some public companies away from quarterly financial reporting toward a semiannual model is drawing significant pushback from investors, even as it continues moving through the regulatory process. The debate has direct implications for corporate finance teams, auditors, and the broader transparency of U.S. capital markets.
What the SEC Proposed
According to a summary published by accounting advisory firm Cohen & Co., the SEC issued a proposed rule on May 19, 2026, aimed at simplifying financial reporting requirements for many U.S. public companies. The proposal would potentially reduce the frequency of certain mandatory disclosures from quarterly to semiannual, a structural change that has not been made to core U.S. reporting requirements in decades.
The proposal follows an extended debate within U.S. policy circles, with proponents arguing that reduced reporting frequency could lower compliance costs and free up management time for longer-term strategic planning rather than quarter-to-quarter results management.
Why Investors Are Pushing Back
Comment letters submitted in response to the proposal have been extensive, and according to Cohen & Co.’s review of the public record, investors “appear to be largely opposed” to the shift, viewing frequent interim reporting as a core benefit of U.S. capital markets relative to other jurisdictions.
Accounting and law firms have taken a more measured position, generally urging any changes to remain aligned with the Financial Accounting Standards Board (FASB), whose existing disclosure requirements and guidance are built around a quarterly reporting cadence. A shift to semiannual reporting without corresponding changes to FASB guidance could create friction between SEC filing requirements and GAAP-based disclosure expectations.
Lessons From the U.K. Experience
The debate is not without precedent. The United Kingdom moved away from mandatory quarterly reporting for listed companies in 2014, returning to a semiannual disclosure requirement. According to Cohen & Co.’s analysis, that experience offers a cautionary data point: there was no measurable increase in capital expenditure or R&D investment following the change, while analyst coverage of affected companies declined as reliable interim information became less available — a particular risk for smaller and newly public companies that rely on analyst coverage to maintain investor visibility.
Practical Implications for Finance Teams
Beyond the debate over disclosure philosophy, the proposal carries practical complications. Many companies have debt covenants and credit agreements structured around quarterly financial delivery; a shift to semiannual reporting could require renegotiating those terms. Reduced reporting frequency would also extend the “window of market silence” between disclosures, a factor that governance and investor-relations teams would need to manage carefully to avoid information asymmetry.
Separately, and unrelated to the reporting-frequency debate, the SEC and FASB have continued finalizing more routine updates this year. New Accounting Standards Updates are taking effect for December 31, 2026, fiscal year-ends covering income tax disclosures, credit loss measurement, induced debt conversions, and stock compensation, according to Eide Bailly’s review of 2026 ASU activity. Additional guidance on paid-in-kind dividends and environmental credits is also on the near-term horizon.
What to Watch Next
The semiannual reporting proposal remains in the comment and review phase, and no final rule has been adopted as of this writing. Finance leaders should monitor the SEC’s regulatory agenda for further movement, while treating the current quarterly reporting requirement as the operative standard until any final rule is issued and an effective date is set.
Given the extent of investor opposition documented in the comment file, a full shift to mandatory semiannual reporting appears more likely to result in either a scaled-back compromise or continued study rather than swift adoption — though the SEC’s ultimate direction remains uncertain.