Accounting
Congress passes Trump tax bill

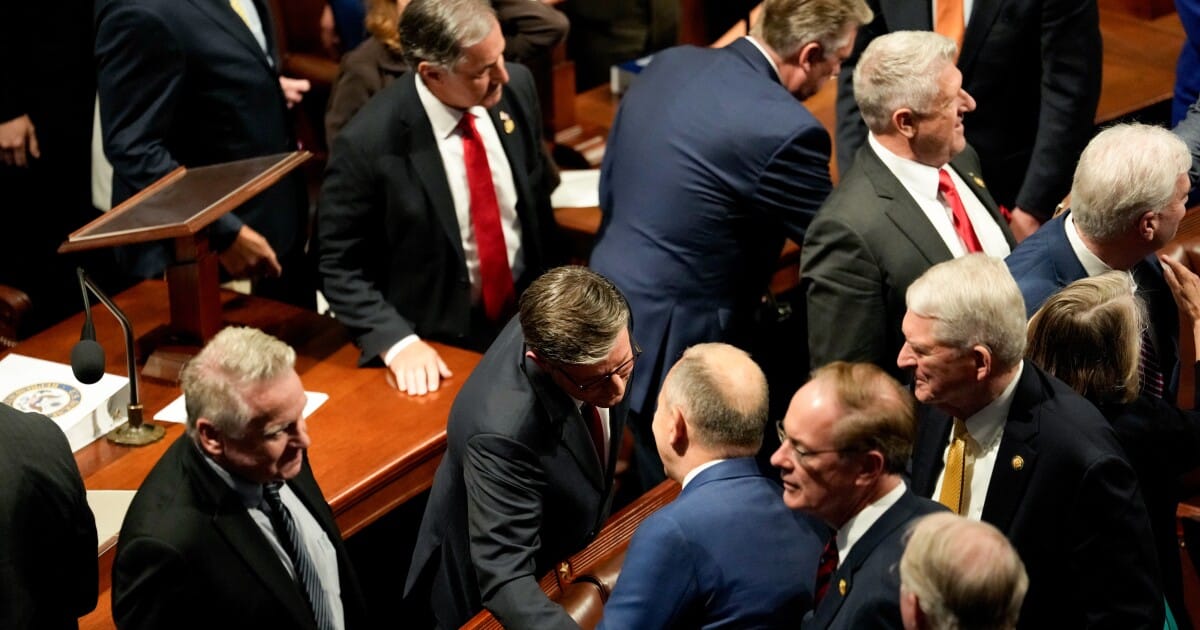
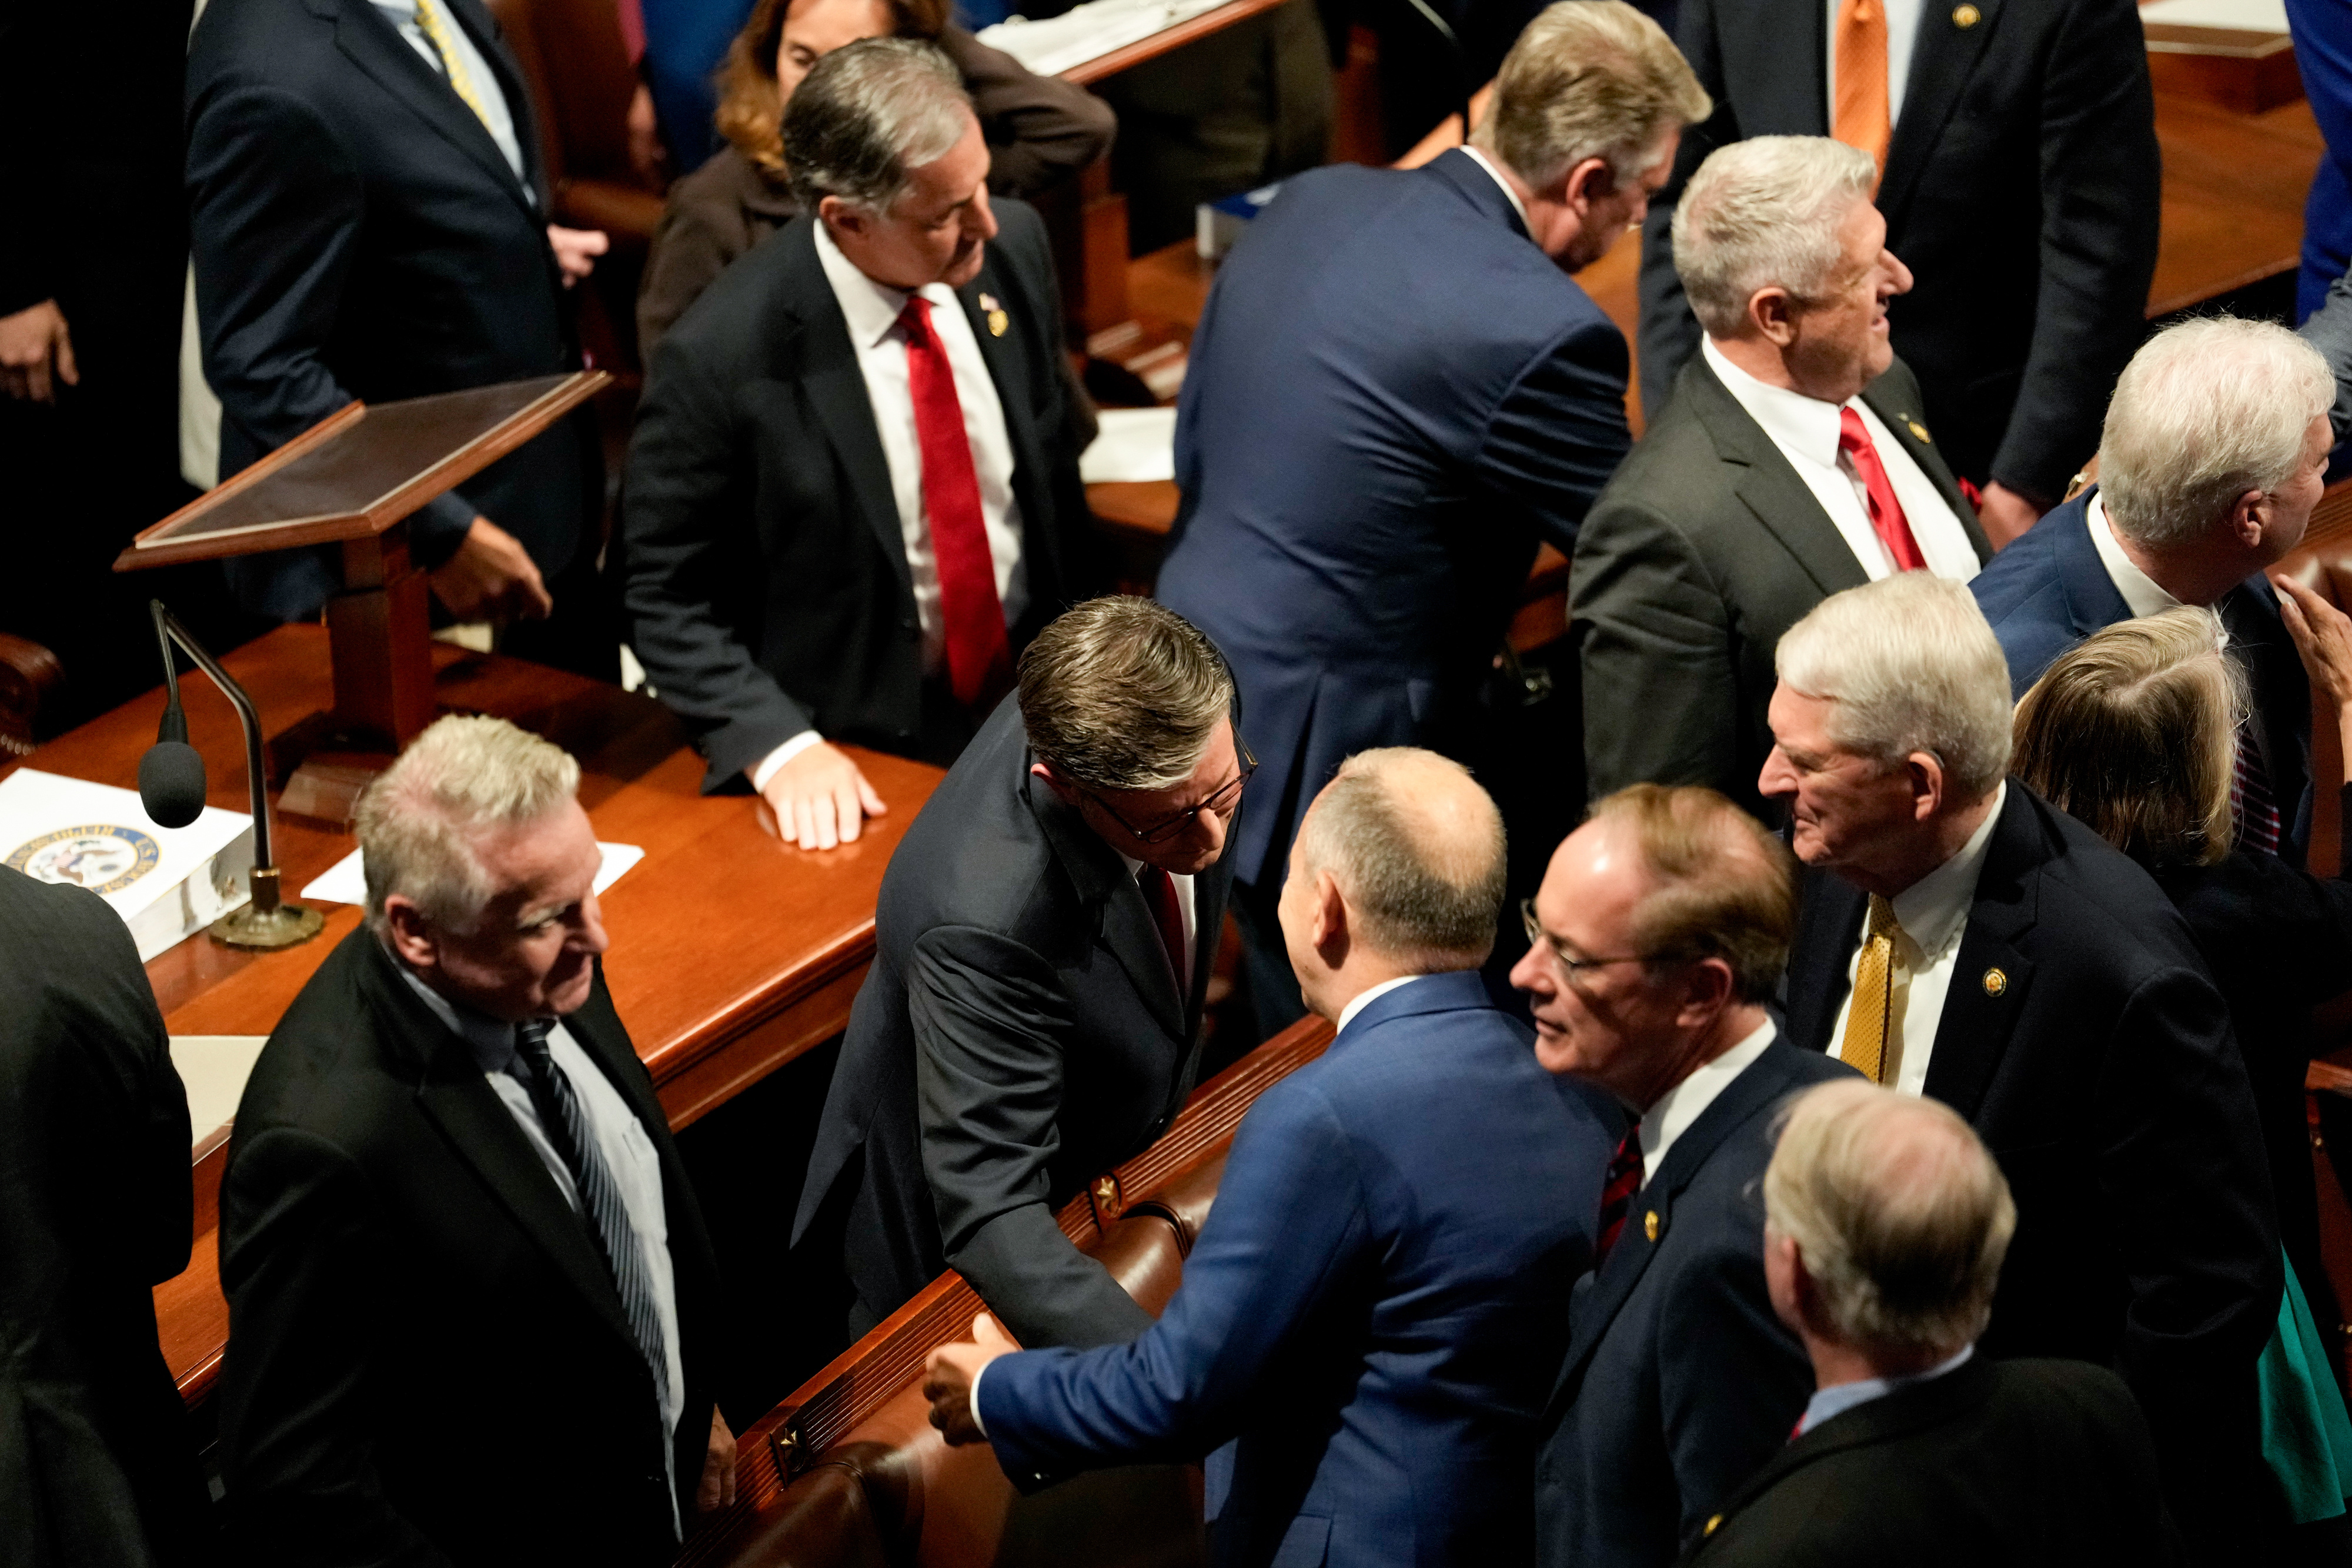
House Republicans passed the wide-ranging Trump tax legislation dubbed the One Big Beautiful Bill Act, overcoming resistance from a group of GOP holdouts and united opposition from Democrats.
The bill passed by a vote of 218 to 214, mainly along party lines with only two no votes from Republicans, Thomas Masie of Kentucky and Brian Fitzpatrick of Pennsylvania.
The bill would extend the expiring tax breaks from the Tax Cuts and Jobs Act and make many of them permanent. A summary of the main provisions can be
House Minority Leader Hakeem Jeffries, D-New York, spoke out extensively against the bill, which he dubbed the “one big ugly bill” during a record-breaking marathon speech lasting over eight hours and 44 minutes in a last-ditch effort to delay the bill from being passed. He repeatedly denounced the cuts to Medicaid and the Supplemental Nutrition Assistance Program to fund the tax cuts.
The legislation makes extensive tax changes and preserves the expiring tax breaks from the TCJA.
“It’s important that some of the provisions of the Tax Cuts and Jobs Act not be allowed to expire,” said Tom O’Saben, director of tax content and government relations at the National Association of Tax Professionals. “That’s part of what’s making the headlines. It’s really important legislation to get many of those provisions continued.”
Among the key provisions that have been under negotiation are the expansion of the so-called SALT cap for state and local tax deductions, which is going to be increased to $40,000 for five years.
“That’s going to give people who have more than $10,000 in state and local taxes, local property taxes, etc, the ability to possibly benefit from that,” said O’Saben. “They’ve still got to get over the standard deduction, which is also increased in the One Big, Beautiful Bill, but not to the extent where standard deductions were basically doubled under the original Tax Cuts and Jobs Act. It is possible that many taxpayers may still not benefit from the increase in the SALT limitation.”
“It’s generally looked at as a tax and spending bill, and that is a big portion of what it does,” said Casey Burgat, an assistant professor and director of legislative affairs at George Washington University. “On the tax side, it will obviously extend the Trump tax cuts passed in 2017. Those things will continue to benefit the wealthy disproportionately. It will explode the deficit, despite Republicans claiming that we’re going to grow our way out of this, and then there’s a lot of smaller provisions that will affect a lot of people’s everyday lives, especially those at the bottom of the income food chain.”
He believes the bill will give tax professionals plenty of work in the future to help their clients.
“I’d imagine that accountants and tax professionals will benefit from this, in that there’s going to be changes, and you need businesses to rely on you to explain what’s going on, to talk about the changes in regulations and what type of benefits or tax credits your company or an individual can qualify for,” said Burgat. “While this is an extension of the biggest piece of tax cuts with the Trump income tax brackets, there’s a lot of changes, including eliminating a lot of those tax credits, particularly on the green economy side that were included in the Inflation Reduction Act during the Biden administration.”
The legislation takes aim at the tax credits won for the renewable energy industry from the Inflation Reduction Act.
“Most of corporate America spent 2025 playing defense in Washington, trying to convince lawmakers not to raise their taxes,” said John Gimigliano, co-lead of the federal legislative and regulatory services group in the Washington National Tax at KPMG LLP, in a statement. “In the end, the business community comes away from the Senate bill avoiding most of their worst-case scenarios. One notable exception to this of course is the renewable sector. Wind and solar developers in particular would see a rapid phase out of the tax credits they rely on to support the economics of those investments. For many in that sector, this bill would represent their fears confirmed.”
Tax breaks for tips and overtime are also important tax considerations. “My concern was how that’s going to work, and I think that’s what tax professionals will be mostly interested in,” said O’Saben. “What do we do on Monday morning, July 7, when this becomes the law if you happen to be a company that does payroll, or you work with small businesses? It would appear that the deduction for tips or overtime will truly be at the individual employee level, meaning there’s going to be a deduction on the 1040. What we’re guessing at NATP is how that’s going to be handled. The challenge for employers or payroll services will be to identify on the W-2 when it’s issued at the end of the year on payroll reports as they go through the year as to what amount of cash tips did the employee incur, or what amount of overtime did they incur?”
While Trump’s campaign promises for tax breaks on overtime pay and tips are in the bill. the limits on Social Security aren’t fully there. “The other big proposal that I’m actually disappointed with is that the President talked about Social Security not being taxed, and in both the House and Senate versions, what they’ve come up with is a senior deduction,” sad O’Saben. “The original House version was $4,000 per person, so a grand total for a married couple of $8,000. The Senate version was $6,000, so that would be $12,000 for a married couple if they’re both age 65 or over. That’s a far cry from making Social Security benefits not taxable.”
“I’m a tax professional , and clients have said at least I don’t have to claim my Social Security benefits this year. Not so,” O’Saben cautioned. “You’re still going to have to claim your Social Security benefits, but if you’re a senior receiving Social Security benefits, then you’ll have this senior deduction.”
Businesses will be able to benefit from the return of 100% bonus depreciation. “Bonus depreciation was phasing out, and in 2025, I believe, was down to about 40% of the cost of an item placed in the service during the year,” said O’Saben.
Another provision involves Trump savings accounts for children. “If there’s children under the age of five, born in 2025 to 2028, there’s going to be a savings account opened for babies fed by the government with $1,000 and then families or grandparents can add to these accounts to a limit of $5,000,” said O’Saben. “That might be an interesting thing to see to help spur some savings for children as time goes on.”
The NATP had worked with the AICPA on beating back a provision in the House version of the bill that would have limited the SALT deduction for pass-through businesses like accounting firms, and it wasn’t preserved in the Senate version of the bill that was passed by the House.
The American Institute of CPAs issued a statement lauding passage of the bill. “The passage of the One Big Beautiful Bill Act, which includes a number of important provisions beneficial to the accounting profession, is a win for millions of businesses, taxpayers and tax practitioners across the country,” said AICPA president and CEO Mark Koziel in a statement. “Among the numerous provisions supported by the AICPA, this bill expands the use of section 529 accounts for costs associated with obtaining a post-secondary credential; repeals the lowered threshold for Form 1099-K; makes permanent 100 percent bonus depreciation; makes permanent the section 199A qualified business income deduction; extends and enhances the Paid Family and Medical Leave Tax Credit; removes the restriction on the regulation of contingency fees; retains current rules around the excess business losses limitations; and removes the limit on pass-through businesses’ state and local tax (SALT) deductions.
“We are thankful to the members of Congress who supported millions of businesses’ ability to retain pass-through entity tax SALT deduction and our partners throughout the state CPA societies and other professional service businesses for their diligent advocacy on this important issue,” Koziel added. “No bill is perfect — however, there are many beneficial tax provisions in this bill that I believe support the business community and will help grow our economy. The tax provisions in this bill will help facilitate tax planning earlier in the year, which can help reduce the anxiety of the unknown for many taxpayers. We look forward to continuing our work with Congress and the Administration to improve these provisions as they are implemented.”
“It appears that the Senate heard the AICPA and they heard us in saying that we found that was not fair,” said O’Saben. “If your friend has a flower shop right next to you, and you’re an accountant in the next building, the flower shop qualifies for a higher SALT limitation, and you don’t, so that didn’t seem to make any sense.”
Accounting
Embedded AI and Automated Anomaly Detection Reshape Modern Corporate Accounting Frameworks


Dario Amodei’s Call to Pace the AI Frontier and Its Market Ripple Effects

Rising Oil Prices And Persistent Inflation Complicate Fed Decision

Bridging the AI Skills Gap: How Gen Z Youth Demographics Are Transforming the Workforce

Armanino adds Strategic Accounting Outsourced Solutions

New 2023 K-1 instructions stir the CAMT pot for partnerships and corporations

Tax Strategy: Employee Retention Credit update
-
 Stock News1 week ago
S&P 500 September Outlook: Tech Rally Holds Index at 7,600
-
 Finance1 week ago
S&P 500 Outperforms Amid Strong Corporate Earnings as Treasury Yields Cap Equity Multiples
-
 Accounting1 week ago
Mandatory ESG Reporting Standards Demand Standardized Non-Financial Audit Trails
-
 Insights1 week ago
Climate Resilience and Offshore Wind and Land Restoration Milestones
-
 Leaders1 week ago
India Unveils ‘Saptadhara’ Reform Agenda Targeting Technology, Youth Skilling, and Growth
-
 Economics1 week ago
U.S. Inflation Outlook for 2027
-

 Economics4 days ago
Economic Profile of the superpower of western Europe
-
 Economics4 days ago
Sovereign Bond Yield Volatility and Inflationary Shocks Challenge Global Central Banks