Finance
How Italy’s banking M&A wave started crashing

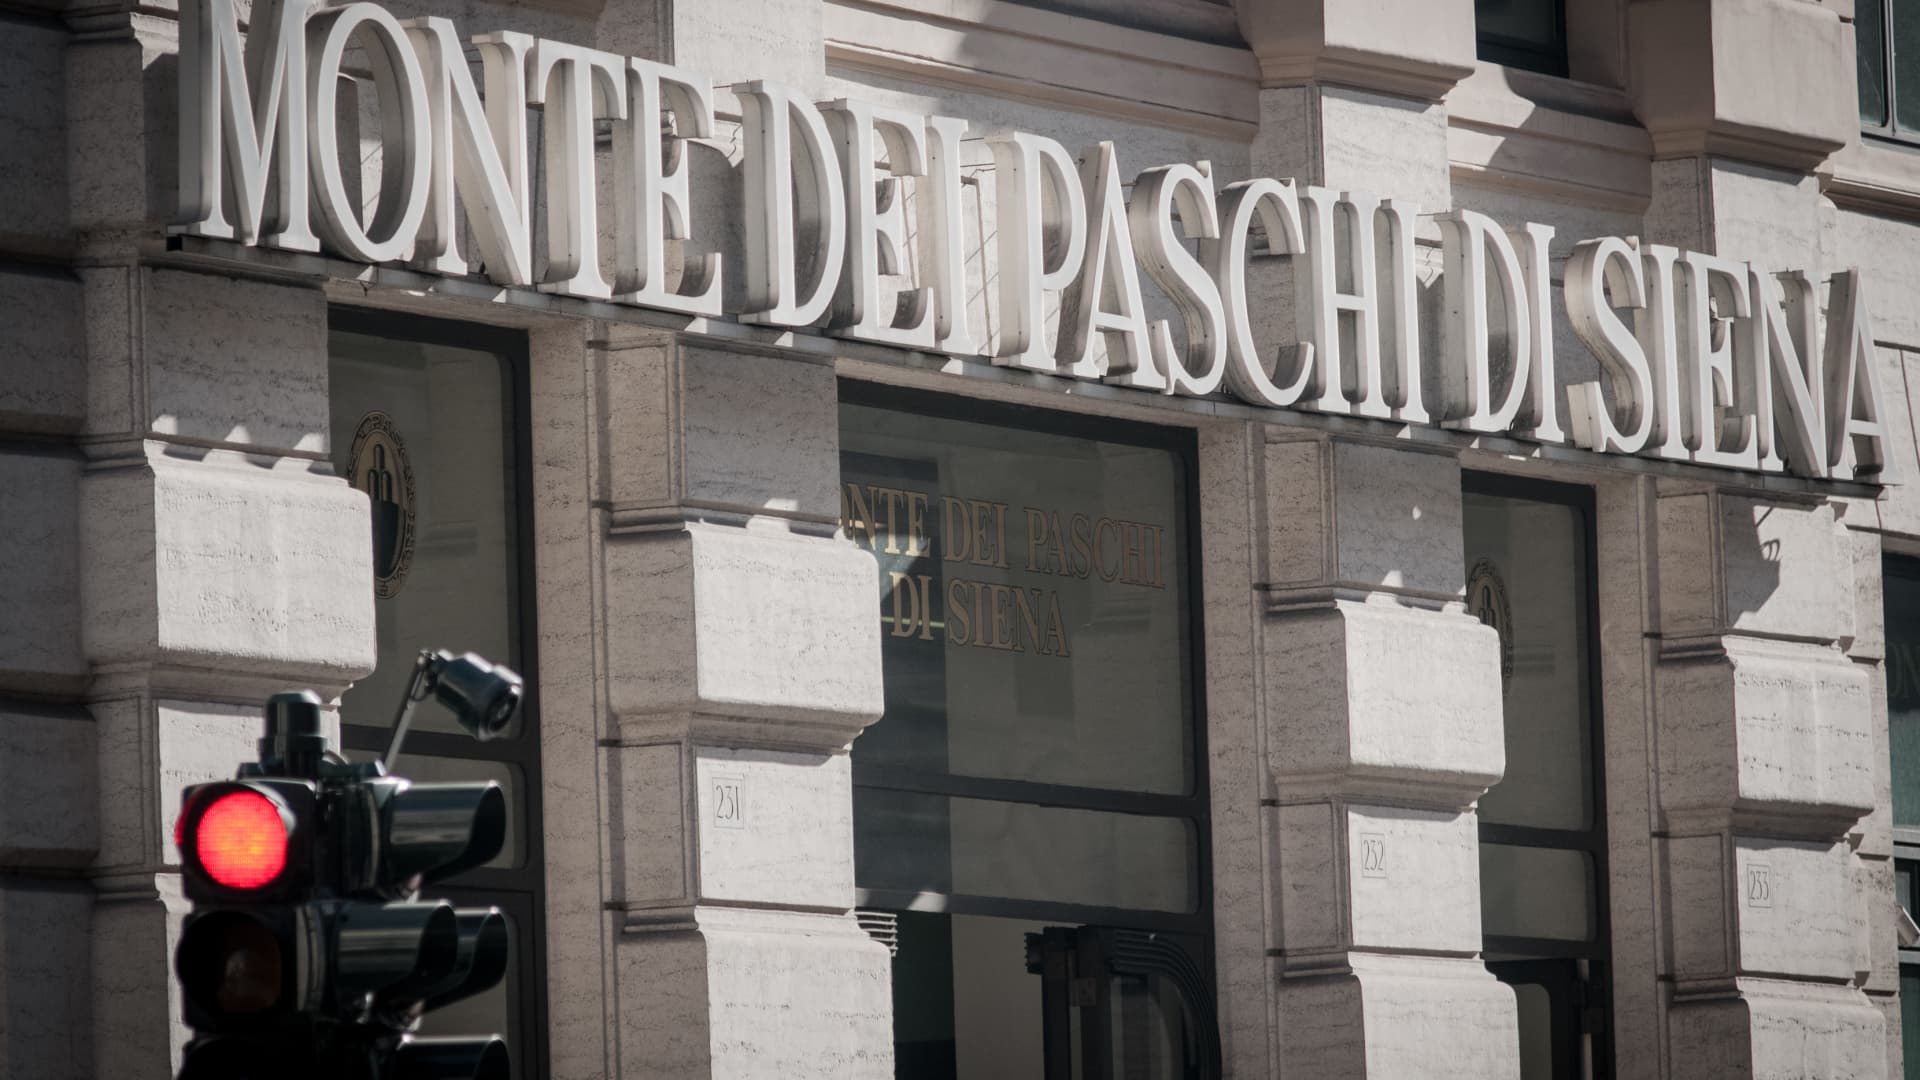
View of the branches of the Italian bank Monte deo Paschi in Rome.
Nurphoto | Nurphoto | Getty Images
By late spring, Italy’s banking world was swept up in a storm of convoluted takeover bids and counterbids involving a swathe of the country’s major lenders. Three months later, only one high-profile bid is still standing.
It started with UniCredit‘s July decision to drop the “drag” of its nearly 15-billion-euro ($17.5-billion) bid for Banco BPM on the cusp of the proposal’s natural expiry, citing the opacity of conditions imposed by the Rome administration via its “golden power” screening rules. Then, Mediobanca‘s shareholders this month voted against the lender’s roughly 7-billion-euro offer for Banca Generali, thwarting what was widely seen as a defensive play against state-backed Monte dei Paschi‘s (MPS) interest in at least 35% of Mediobanca.
MPS has yet to give up.
Consolidation is one recourse for Europe’s cash-flush lenders to bulk up their scale and compete with Wall Street’s historically more lucrative banking giants. The M&A appetite has gripped Europe’s lenders at a time of markedly improved performance in the sector, with restructuring programs, the European defense boost, higher investment banking returns amid U.S. tariff-led volatility and an increase in broader M&A dealmaking in Southern Europe bolstering bottom lines.
In particular, the entangled web of offers from several of Italy’s key lenders — with pack leader Intesa Sanpaolo notably absent — builds on long-brewing momentum in what Fitch Ratings in April billed as a “more fragmented” banking system than in some other European nations.
“Increased scale could enable banks to better support large corporate investments, including those linked to European and Italian defence sector initiatives,” the agency said at the time.
Italy’s economy has been fertile ground for banking growth of late. It has “outperformed most of its Eurozone peers in recent years, although momentum may ease in coming years as an investment boom driven by [Next Generation EU] funds and construction spending fades away,” Deutsche Bank analysts said in an August report, stressing the country will need to pivot toward a more consumption-driven economy — facing the incoming pressures of higher U.S. tariffs.
The International Monetary Fund forecasts Italy — where it pronounced “further improvement in banking sector soundness” in a July report — will notch 0.5% economic growth this year, outpacing Germany’s projected 0.1% expansion over the same period.
M&A run still to go
While the pace of Italy’s consolidation attempts has simmered, analysts say we’re far from a denouement.
“Of late we have seen Banca BPER successful taking over Banca Sondrio, and Illimity Bank acquired by Banca Ifis. Meanwhile Monte dei Paschi is resolutely marching on Mediobanca, and Banco BPM’s independence might be short-lived, with Credit Agricole launching towards a 20% stake,” said Filippo Maria Alloatti, head of financials for credit at Federated Hermes Limited. “A merger between Credit Agricole Italy and Banco BPM seems likely in the medium-term.”
He added that the odds of MPS prevailing in its offer for Mediobanca are now higher — a view echoed by William Cain, head of M&A Research EMEA at Mergermarket, who told CNBC that “the vote on Banca Generali was effectively a referendum on Mediobanca’s standalone strategy and shareholders have now made their views clear on that point.”
He went on to say that, “There is an increasing chance BMPS will secure the 35% of Mediobanca’s share [that] capital management has previously said it would be happy with – and perhaps a lot more.”
Italy’s banks have also set sights beyond the country’s borders. UniCredit’s first play last year was to progressively accrue a synthetic stake of up to roughly 28% in German lender Commerzbank. The Italian bank has since converted this into a 26% equity shareholding in Commerzbank and has secured the European Central Bank’s blessing to hold up to 29.9% — stirring speculation over plans for a potential takeover, which Commerzbank and the Berlin administration have resisted.
The same UniCredit on Thursday said it has raised its holding in Greece’s Alpha Bank to nearly 26%, after engaging financial instruments for an additional 5% stake.

“What’s happening is not just an Italian story – Italy has become an important case study for the EU to test how M&A can evolve in the European banking sector,” Stefano Caselli, dean of the SDA Bocconi School of Management, told CNBC by email.
The consolidation fever has indeed spread beyond Italy. In July, Spain’s Banco Santander said it was buying British high street bank TSB for £2.65 billion from Sabadell. The Catalonian lender has itself been fighting off the advances of Spanish peer BBVA, which has decided to keep its takeover bid alive despite strict conditions from the Madrid government to clear the transaction.
The EU has challenged Spain over its intervention in the BBVA bid and has likewise found itself at odds with Rome over its use of the “golden powers” rules, which are typically invoked against transactions that threaten national security, in the UniCredit takeover. The European Commission has also posed questions over the Italian government’s November sale of a 15% stake in the bailed-out MPS, in which Rome retains a 11.73% shareholding. Italian Finance Minister Giancarlo Giorgetti has defended the “absolute correctness” of the stake exit, separately threatening to resign if he were overruled on the conditions Rome imposed on UniCredit, which included a timeline for the lender to halt its activities in Russia and a request to leave Banco BPM’s loan-to-deposit ratio unchanged for five years.
“The Italian Finance Ministry’s intervention was the final nail on the coffin for UniCredit’s 3rd takeover attempt at Banco BPM,” Alloatti pronounced.
In the case of the MPS bid, the SDA Bocconi School of Management’s Caselli argued that Rome “simply acted as a shareholder.”
“On the one hand, we expect the State to step in when a bank is in trouble. On the other hand, we want taxpayers not to lose money but ideally to see gains. At the same time, we want the State to play a neutral role,” Caselli said. “It’s difficult to achieve all of this at once.”
EU scrutiny
The EU, a proponent of lender consolidation, has launched the banking union supervision framework since the financial crisis, but is yet to complete the initiative.
“Hopes that the banking union would lead to closer integration of banking markets across Europe have not fully materialized,” Claudia Buch, chair of the supervisory board of the ECB, said in April. “Cross-border mergers have remained relatively rare, about 75% of banks’ lending portfolios are invested in their home markets, and few banks have truly European business models.”
Tie-ups have dwindled the number of EU banks since 2009, although roughly 4,752 were still operating in the European Union as of June, with 418 in Italy, according to Statista.
And the lack of blockbuster cross-border tie-ups is grinding some gears within the bloc.
“I feel frustrated because I continue to see domestic mergers with a domestic logic, not single-market mergers,” European Banking Authority Chairman Jose Manuel Campa told Politico earlier this week.


Dario Amodei’s Call to Pace the AI Frontier and Its Market Ripple Effects

Rising Oil Prices And Persistent Inflation Complicate Fed Decision

Bridging the AI Skills Gap: How Gen Z Youth Demographics Are Transforming the Workforce

Armanino adds Strategic Accounting Outsourced Solutions

New 2023 K-1 instructions stir the CAMT pot for partnerships and corporations

Tax Strategy: Employee Retention Credit update
-
 Stock News1 week ago
S&P 500 September Outlook: Tech Rally Holds Index at 7,600
-
 Finance1 week ago
S&P 500 Outperforms Amid Strong Corporate Earnings as Treasury Yields Cap Equity Multiples
-
 Accounting1 week ago
Mandatory ESG Reporting Standards Demand Standardized Non-Financial Audit Trails
-
 Insights1 week ago
Climate Resilience and Offshore Wind and Land Restoration Milestones
-
 Leaders1 week ago
India Unveils ‘Saptadhara’ Reform Agenda Targeting Technology, Youth Skilling, and Growth
-
 Economics1 week ago
U.S. Inflation Outlook for 2027
-

 Economics5 days ago
Economic Profile of the superpower of western Europe
-
 Economics5 days ago
Sovereign Bond Yield Volatility and Inflationary Shocks Challenge Global Central Banks