Connect with us

Finance

Pickleball is just getting started in China

Published

on

Sports club Suzhou Shishan opened the Chinese city’s first pickleball court in January 2024, according to the company.

Suzhou Shishan

BEIJING — While the U.S. pickleball craze is still going strong, China’s is only just getting started.

Online sales of pickleball paddles and related equipment in China have skyrocketed this year to an average of $1.2 million in monthly sales as of July — an increase of more than six-fold versus the year-ago period.

That’s according to data from WPIC Marketing + Technologies. The company helps foreign brands — such as Ohio-based food blender seller Vitamix and skincare brand iS Clinical from California — sell online in China and other parts of Asia.

“Pickleball’s rise in China reflects a broader shift toward active lifestyles and recreational sports participation,” said Jacob Cooke, co-founder and CEO of WPIC.

The racquet sport has been getting a lift from social media influencers and the resurgence of tennis in China, thanks in part to Chinese tennis player Zheng Qinwen winning the country’s first Olympic gold medal in tennis singles last summer, Cooke said.

DC Open's Mark Ein on the economics of tennis, brand sponsorships and future of sports rights

Interest in tennis and pickleball in China started in 2023, accelerated in 2024 and is “still doing very well” this year, said Daniel Zipser, senior partner at McKinsey and leader of its Asia consumer and retail division. “We’re still now in the very strong acceleration growth momentum [period] for racquet sports more broadly.”

He pointed out that locals are not just increasingly picking up the sport, but also watching professional games more.

During the U.S.-based Professional Pickleball Association’s (PPA) first “Hong Kong Open” competition from Aug. 21 to Aug. 24, “there was actually a pretty big crowd that came out [to watch the] final gold medal matches,” said Patrick Yan, founder of The Brine Agency, which represents Asian pickleball players. “The entire tournament was maxed out and with a waitlist.”

Yan also noted that the Hong Kong region now has many more pickleball courts compared to only two when he visited in December and January.

The Hong Kong Open was part of the inaugural PPA Tour Asia that includes matches in Japan, Malaysia and Vietnam.

Jack Wong of Hong Kong won the men’s singles championship, while Roos van Reek of the Netherlands won in women’s singles. The PPA did not immediately respond to a request for comment on whether a “China Slam” initially set for early October was moving ahead as planned.

The PPA held its first U.S. pickleball tournament in Arizona in early 2020. The sport surged in popularity during the pandemic as communities quickly repurposed public spaces into free pickleball courts. Since then, pickleball has been the fastest-growing sport in the United States for four straight years, according to the latest Sports and Fitness Industry Association report in May.

Business angle

Pickleball’s recent growth in China has different business implications.

In contrast to U.S. suburbs, big Asian cities don’t tend to have large neighborhood spaces, Yan pointed out. “All these courts have to be built by people running businesses. They’re operating for profit…. People started seeing it could be a huge profit, all these competing businesses and startups.”

He added that the local pickleball tournament system is run by the national Chinese Tennis Association, making the sport’s development “quite systemized in comparison to other countries where it’s local organizations that have to organize and fund everything.”

Lu Bing, deputy head of the Suzhou Pickleball Association, said he learned about pickleball from an American friend in 2023. Subsequently, the local Shishan sports club that he is general manager of opened several pickleball courts, where hourly fees start at 60 yuan ($8.39). He added that many local schools are also encouraging students to play the sport by repurposing basketball courts and other facilities, he said.

Part of pickleball’s appeal in China is how easy it is for locals to learn the sport — some people still found tennis too hard after a few lessons at the sports club, he added.

Challenges and opportunities

While Lu said the club is an authorized sales partner for Joola, a U.S. pickleball brand, it’s less clear how easily other foreign brands and organizations can immediately tap into the trend.

Despite China’s large potential compared to Vietnam and Malaysia, which are Asia’s largest pickleball markets, it can be difficult for foreign businesses to navigate the Asian giant’s market due to language barriers and the unique WeChat messaging app-based ecosystem, Yan said.

“I know eventually probably some courts will go out of business and some will survive and take over the market in certain areas,” he said. “Because it’s so early into the market, a lot of people are trying to be the first mover basically.”

The surge of consumer spending on pickleball and other sports in China comes as overall retail sales have been subdued since the pandemic.

McKinsey’s Zipser said he’s “very confident” about a pickup in consumption in the second half of this year into 2026, as he thinks consumer spending is now more detached from depressed sentiment.

“The last two years the consumer was just waiting for the good old days to be back,” he said, pointing to hopes for a recovery in the property market and broad double-digit growth.

“People now have realized [that’s] not going to happen,” he said. “They’ve moved on. They’re no longer sitting there. … Life needs to go on.”

Continue Reading

Finance

Big Tech Enterprise Borrowing Reaches $135 Billion as Hyperscalers Fund AI Infrastructure

Published

on

Big Tech Enterprise Borrowing Reaches $135 Billion

Corporate debt markets are undergoing a major structural shift as major technology hyperscalers execute unprecedented debt offerings to finance large-scale artificial intelligence infrastructure. According to institutional market estimates, the annual value of debt issued by top technology firms reached $135 billion in 2026, marking a massive increase from the $35 billion annual average recorded between 2020 and 2024. This wave of corporate borrowing reflects the immense capital required to build next-generation data centers, secure specialized silicon, and build energy infrastructure.

The scale of AI-driven capital expenditures is reshaping corporate finance frameworks. While tech giants historically maintained fortress balance sheets dominated by cash reserves and minimal debt liabilities, the speed of the AI infrastructure deployment race has led corporate treasurers to access debt capital markets. These multi-billion-dollar corporate bond issuances are competing directly with sovereign debt for institutional investment capital.

Credit rating agencies and fixed income analysts are evaluating the long-term balance sheet implications of this corporate borrowing boom. While technology hyperscalers possess substantial revenue streams and strong operating margins, the high interest rate environment means new debt issuances carry higher coupon burdens. Financial analysts are closely tracking return-on-investment (ROI) metrics to ensure capital outlays generate sufficient cash flow to service expanding debt obligations over the coming decade.

Despite elevated borrowing costs, primary market demand for high-grade technology bonds remains robust. Institutional asset managers, pension funds, and insurance firms are absorbing new issuances, attracted by investment-grade credit ratings and attractive yields. However, the concentration of corporate debt issuance within the technology sector highlights growing exposure to enterprise technology spend cycles.

Why This Information Matters
The massive surge in technology sector debt issuance impacts broader credit markets and institutional liquidity. For corporate leaders and investors, understanding how major enterprise tech firms fund infrastructure expansion provides key insights into market interest rate dynamics, corporate credit availability, and the long-term ROI expectations driving modern corporate finance.

Continue Reading

Finance

S&P 500 Outperforms Amid Strong Corporate Earnings as Treasury Yields Cap Equity Multiples

Published

on

S&P 500 Outperforms Amid Strong Corporate Earnings as Treasury Yields Cap Equity Multiples

Financial markets opened September on a firm footing following a solid performance in August, where the S&P 500 gained 2.6% and the tech-heavy Nasdaq Composite rose 3.9%. Corporate earnings across major index constituents showed impressive momentum, with S&P 500 year-over-year earnings growth topping historic averages. However, despite robust corporate balance sheets, equity market valuations face headwinds as benchmark 10-year Treasury yields remain elevated near 4.75%.

The current financial environment is characterized by a strong divergence between corporate earnings resilience and bond market pressure. Enterprise technology leaders, financial institutions, and consumer sectors reported strong profit margins, benefiting from operational efficiency gains and disciplined cost management. Yet, institutional investors remain cautious about expanding price-to-earnings multiples when risk-free benchmark bond yields offer yields near 4.7%.

Fixed income markets continue to reflect restrictive monetary conditions. The broader aggregate bond market recorded flat total returns year-to-date, while fixed income yields—such as 30-day SEC yields on core bond funds—stayed above 4.6%. This yield profile provides institutional and retail investors with meaningful cash flow returns without taking on equity market downside risk, creating a competitive alternative for institutional capital allocation.

Portfolio managers and investment strategists recommend a disciplined, quality-oriented approach entering the final quarter of 2026. Rather than chasing speculative momentum, capital flows are favoring companies with strong cash flow generation, low debt-to-equity ratios, and robust pricing power capable of withstanding elevated input costs.

Why This Information Matters
The tension between strong corporate earnings and elevated bond yields directly impacts portfolio allocations and retirement wealth. Individual investors and wealth managers must balance equity market participation with fixed-income yield opportunities, ensuring portfolios are diversified against sudden valuation adjustments caused by fluctuating benchmark interest rates.

Continue Reading

Finance

Treasury Bond Volatility Forces Bessent to Double Debt Buyback Size as Yields Swing

Published

on

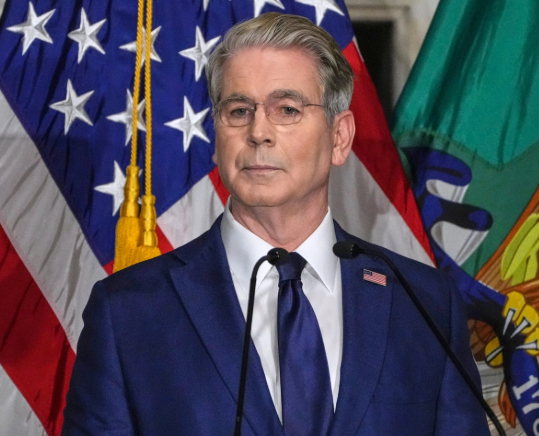
Bessent

A turbulent week in the U.S. Treasury market prompted the Treasury Department to sharply increase the size of its long-term debt buyback program, as bond prices fell even while equity markets pushed toward record highs. The divergence has drawn attention from fixed-income strategists who see it as a signal of underlying investor unease about federal borrowing levels.

What Happened This Week

U.S. Treasury Secretary Scott Bessent told CNBC on Thursday, August 20, 2026, that the Treasury had doubled the size of its long-term debt buyback operations, moving from roughly $2 billion to at least $4 billion per operation. Bessent indicated the figure could climb further, saying “we’re going to increase the size of the buyback,” and noted the accelerated pace could exceed the announced $4 billion threshold per issue.

Buybacks allow the Treasury to repurchase outstanding government bonds directly from the market, which can help support prices and dampen yield volatility during periods of stress. The expanded program came as stocks staged a late-week recovery: the S&P 500 and Russell 2000 both advanced on Friday, August 21, even as Treasuries logged mild losses, according to Bloomberg market data.

Why Bond and Equity Markets Are Diverging

Capital.com senior market analyst Daniela Hathorn described the week’s dynamic as markets “ending the week on a softer tone after the relative calm of early August was disrupted by renewed pressure in global bond markets, another rise in oil prices, and growing uncertainty around the Federal Reserve’s next move.” She noted that higher long-term borrowing costs are increasingly challenging elevated equity valuations, even as U.S. equities pull back modestly from record highs.

This divergence — equities near record levels while bonds sell off  is unusual and reflects two different sets of investor concerns. Equity investors have remained focused on corporate earnings strength, particularly from large technology companies ahead of Nvidia’s closely watched August 26 earnings report. Bond investors, by contrast, are more directly exposed to concerns about the scale of federal borrowing, highlighted this week by the national debt crossing the $40 trillion threshold for the first time.

The Fed and Treasury “Working in Opposite Directions”

Wilmington Trust senior bond portfolio manager Wil Stith told Yahoo Finance that current conditions reflect “the Fed and the Treasury basically working in sort of opposite directions,” adding that the imbalance will likely require the Federal Reserve  which he described as having “the larger sandbox”  to adjust the federal funds rate rather than relying on Treasury market interventions alone to manage yields.

Notably, the bond market’s reaction to the Treasury’s buyback expansion was relatively muted; strategists described the move as being largely absorbed without a major rally, suggesting the underlying pressure on yields stems from factors, such as inflation persistence and debt sustainability concerns, that a buyback program alone cannot resolve.

What Comes Next

Markets are now looking to two major events in the days ahead: Nvidia’s earnings report on Wednesday, August 26, and the Federal Reserve’s Jackson Hole Economic Symposium, running August 27-29. This will be the first Jackson Hole gathering under new Fed Chair Kevin Warsh, whose public communication style and policy signals remain less established than his predecessors’, according to market commentary from Regards of Wall Street.

For investors, the key metrics to watch are the size and frequency of future Treasury buyback operations, movements in the 10-year Treasury yield, and any policy signals from Warsh’s keynote address. Continued yield volatility alongside record equity valuations would suggest the market imbalance identified this week has not yet been resolved.


Continue Reading

Trending