Connect with us

Finance

Study reveals retirement costs without Social Security across states

Published

on

Retirement remains top of mind for many Americans, whether they are approaching their so-called “golden years” or have many years to go before leaving the workforce. 

How much money a person needs to have saved to retire without financial stress is an important consideration in the retirement preparation process, and that can vary depending on various factors, including where someone intends to live and their retirement income sources.

A study released this week by GOBankingRates calculated the amount of money that a “comfortable” retirement would require without income from Social Security factored in and the associated yearly expenses a retiree would face in each U.S. state.

RETIREMENT ACCOUNT BALANCES DIP IN THE 1ST QUARTER, BUT SAVERS KEEP CONTRIBUTING
401k pension retirement

A retired couple walks arm in arm on the beach. (Annette Riedl/picture alliance via Getty Images / Getty Images)

The analysis comes as Social Security, a common source of retirement income, is looking at potential financing issues with its trust funds in the future. The trustees for Social Security and Medicare recently found that if Social Security’s Old-Age and Survivors Insurance and Disability Insurance trust funds were combined, the trust funds would be able to pay 100% of scheduled benefits until 2034, one year earlier than reported last year. After that, the trust funds would be able to pay only 81% of scheduled benefits, meaning Social Security recipients would see a mandatory 19% cut automatically. 

For the GOBankingRates study, the benchmark for a “comfortable” retirement was a person holding twice the amount of money as the cost of living expenses.

NEARLY HALF OF GENERATION X IS NOT CONFIDENT ABOUT RETIREMENT

Hawaii tops the list of where the most savings would be necessary to retire “comfortably” at 60 years old without Social Security, while West Virginia, nicknamed the Mountain State, required the least, it said. 

GOBankingRates found the nest egg that a person would need to accommodate a comfortable retirement at 60 years old sans Social Security in each state.

Alabama ($70,492 cost of living per year): $1,409,839 
Huntsville Alabama

Huntsville, Alabama, USA park and downtown cityscape at twilight. (iStock / iStock)

Alaska ($110,457 cost of living per year): $2,209,137

Arizona ($100,281 cost of living per year): $2,005,627

Arkansas ($67,502 cost of living per year): $1,350,045

California ($155,117 cost of living per year): $3,102,333

Colorado ($114,744 cost of living per year): $2,294,882

Connecticut ($105,428 cost of living per year): $2,108,563

Delaware ($94,392 cost of living per year): $1,887,834

Florida ($97,119 cost of living per year): $1,942,374

Georgia ($86,005 cost of living per year): $1,720,096

Hawaii ($186,062 cost of living per year): $3,721,237
The entire coastline of Honolulu, Hawaii

The entire coastline of Honolulu, including the base of Diamond Head crater and state park, past the hotel-lined Waikiki Beach towards downtown in the distance, including the suburban neighborhoods dotting the hills surrounding the city center. (iStock / iStock)

Idaho ($101,912 cost of living per year): $2,038,236

Illinois ($79,736 cost of living per year): $1,594,716

Indiana ($74,029 cost of living per year): $1,480,575

Iowa ($71,373 cost of living per year): $1,427,463

Kansas ($71,534 cost of living per year): $1,430,672

Kentucky ($71,410 cost of living per year): $1,428,204

Louisiana ($67,482 cost of living per year): $1,349,639

Maine ($98,612 cost of living per year): $1,972,231

Maryland ($101,991 cost of living per year): $2,039,812

Massachusetts ($136,626 cost of living): $2,732,517
Boston skyline at sunset from Harvard

Massachusetts came in at number nine among the best states to work remotely. (Joe Sohm/Visions of America/Universal Images Group via Getty Images / Getty Images)

Michigan ($73,780 cost of living per year): $1,475,595

Minnesota ($88,321 cost of living per year): $1,766,414

Mississippi ($65,523 cost of living per year): $1,310,451

Missouri ($73,667 cost of living per year): $1,473,335

Montana ($102,916 cost of living per year): $2,058,322

Nebraska ($76,792 cost of living per year): $1,535,846

Nevada ($103,661 cost of living per year): $2,073,215

New Hampshire ($110,761 cost of living per year): $2,215,216

New Jersey ($118,338 cost of living per year): $2,366,765

New Mexico ($81,627 cost of living per year): $1,632,542

New York ($105,619 cost of living per year): $2,112,384
The New York City skyline

The Manhattan skyline is seen at sunrise from the 86th floor observatory of the Empire State Building on April 3, 2021 in New York City. ((Photo by ANGELA WEISS/AFP via Getty Images) / Getty Images)

North Carolina ($86,857 cost of living per year): $1,737,146

North Dakota ($78,734 cost of living per year): $1,574,682

Ohio ($73,120 cost of living per year): $1,462,391

Oklahoma ($69,161 cost of living per year): $1,383,214

Oregon ($111,541 cost of living per year): $2,230,814

Pennsylvania ($78,582 cost of living per year): $1,571,642

Rhode Island ($109,811 cost of living per year): $2,196,222

South Carolina ($81,586 cost of living per year): $1,631,721

South Dakota ($81,949 cost of living per year): $1,638,979

Tennessee ($81,474 cost of living per year): $1,629,482

Texas ($81,985 cost of living per year): $1,639,693

Utah ($110,623 cost of living per year): $2,212,458

Vermont ($97,999 cost of living per year): $1,959,971

Virginia ($96,141 cost of living per year): $1,922,813

Washington ($126,952 cost of living per year): $2,539,048

West Virginia ($64,715 cost of living per year): $1,294,300

Wisconsin ($84,485 cost of living per year): $1,689,700

Wyoming ($88,792 cost of living per year): $1,775,841
Welcome to Wyoming highway sign along Interstate 90 north of Sheridan. (Photo by: Don & Melinda Crawford/Education Images/Universal Images Group via Getty Images)

Welcome to Wyoming highway sign along Interstate 90 north of Sheridan. (Don & Melinda Crawford/Education Images/Universal Images Group via Getty Images / Getty Images)

In early June, a Gallup survey found 50% of non-retired U.S. adults that own a retirement savings account felt they “expect to have enough to live comfortably in retirement.” 

STUDY SHOWS HOW LONG SOCIAL SECURITY, $1.5M NEST EGG WOULD LAST IN 50 STATES

Confidence was lower among those that lacked a retirement savings account, with only 31% reporting they anticipated having sufficient funds for comfortable golden years. 

Eric Revell contributed to this report. 

Continue Reading

Finance

Big Tech Enterprise Borrowing Reaches $135 Billion as Hyperscalers Fund AI Infrastructure

Published

on

Big Tech Enterprise Borrowing Reaches $135 Billion

Corporate debt markets are undergoing a major structural shift as major technology hyperscalers execute unprecedented debt offerings to finance large-scale artificial intelligence infrastructure. According to institutional market estimates, the annual value of debt issued by top technology firms reached $135 billion in 2026, marking a massive increase from the $35 billion annual average recorded between 2020 and 2024. This wave of corporate borrowing reflects the immense capital required to build next-generation data centers, secure specialized silicon, and build energy infrastructure.

The scale of AI-driven capital expenditures is reshaping corporate finance frameworks. While tech giants historically maintained fortress balance sheets dominated by cash reserves and minimal debt liabilities, the speed of the AI infrastructure deployment race has led corporate treasurers to access debt capital markets. These multi-billion-dollar corporate bond issuances are competing directly with sovereign debt for institutional investment capital.

Credit rating agencies and fixed income analysts are evaluating the long-term balance sheet implications of this corporate borrowing boom. While technology hyperscalers possess substantial revenue streams and strong operating margins, the high interest rate environment means new debt issuances carry higher coupon burdens. Financial analysts are closely tracking return-on-investment (ROI) metrics to ensure capital outlays generate sufficient cash flow to service expanding debt obligations over the coming decade.

Despite elevated borrowing costs, primary market demand for high-grade technology bonds remains robust. Institutional asset managers, pension funds, and insurance firms are absorbing new issuances, attracted by investment-grade credit ratings and attractive yields. However, the concentration of corporate debt issuance within the technology sector highlights growing exposure to enterprise technology spend cycles.

Why This Information Matters
The massive surge in technology sector debt issuance impacts broader credit markets and institutional liquidity. For corporate leaders and investors, understanding how major enterprise tech firms fund infrastructure expansion provides key insights into market interest rate dynamics, corporate credit availability, and the long-term ROI expectations driving modern corporate finance.

Continue Reading

Finance

S&P 500 Outperforms Amid Strong Corporate Earnings as Treasury Yields Cap Equity Multiples

Published

on

S&P 500 Outperforms Amid Strong Corporate Earnings as Treasury Yields Cap Equity Multiples

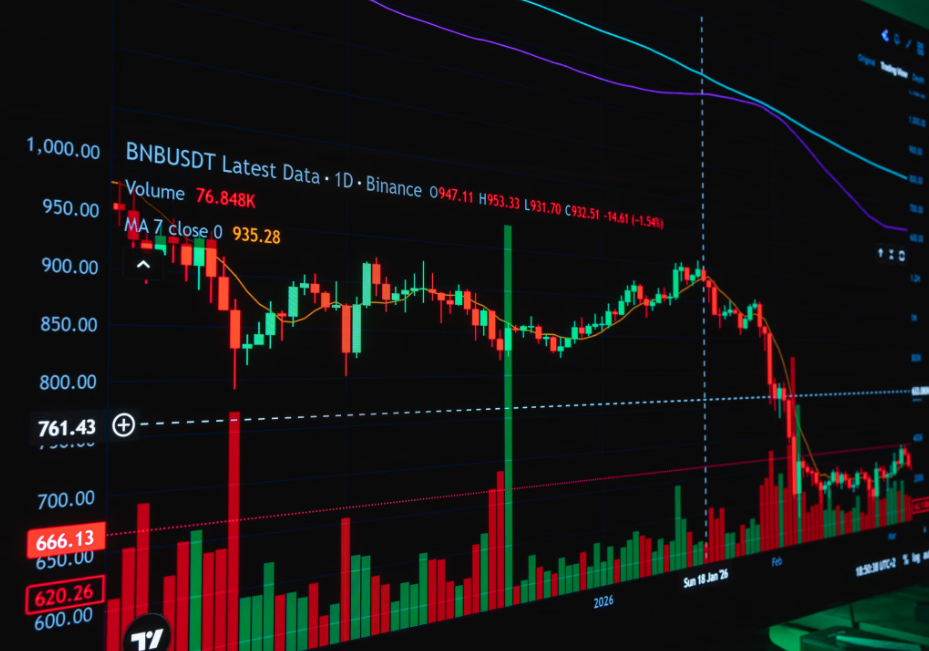
Financial markets opened September on a firm footing following a solid performance in August, where the S&P 500 gained 2.6% and the tech-heavy Nasdaq Composite rose 3.9%. Corporate earnings across major index constituents showed impressive momentum, with S&P 500 year-over-year earnings growth topping historic averages. However, despite robust corporate balance sheets, equity market valuations face headwinds as benchmark 10-year Treasury yields remain elevated near 4.75%.

The current financial environment is characterized by a strong divergence between corporate earnings resilience and bond market pressure. Enterprise technology leaders, financial institutions, and consumer sectors reported strong profit margins, benefiting from operational efficiency gains and disciplined cost management. Yet, institutional investors remain cautious about expanding price-to-earnings multiples when risk-free benchmark bond yields offer yields near 4.7%.

Fixed income markets continue to reflect restrictive monetary conditions. The broader aggregate bond market recorded flat total returns year-to-date, while fixed income yields—such as 30-day SEC yields on core bond funds—stayed above 4.6%. This yield profile provides institutional and retail investors with meaningful cash flow returns without taking on equity market downside risk, creating a competitive alternative for institutional capital allocation.

Portfolio managers and investment strategists recommend a disciplined, quality-oriented approach entering the final quarter of 2026. Rather than chasing speculative momentum, capital flows are favoring companies with strong cash flow generation, low debt-to-equity ratios, and robust pricing power capable of withstanding elevated input costs.

Why This Information Matters
The tension between strong corporate earnings and elevated bond yields directly impacts portfolio allocations and retirement wealth. Individual investors and wealth managers must balance equity market participation with fixed-income yield opportunities, ensuring portfolios are diversified against sudden valuation adjustments caused by fluctuating benchmark interest rates.

Continue Reading

Finance

Treasury Bond Volatility Forces Bessent to Double Debt Buyback Size as Yields Swing

Published

on

Bessent

A turbulent week in the U.S. Treasury market prompted the Treasury Department to sharply increase the size of its long-term debt buyback program, as bond prices fell even while equity markets pushed toward record highs. The divergence has drawn attention from fixed-income strategists who see it as a signal of underlying investor unease about federal borrowing levels.

What Happened This Week

U.S. Treasury Secretary Scott Bessent told CNBC on Thursday, August 20, 2026, that the Treasury had doubled the size of its long-term debt buyback operations, moving from roughly $2 billion to at least $4 billion per operation. Bessent indicated the figure could climb further, saying “we’re going to increase the size of the buyback,” and noted the accelerated pace could exceed the announced $4 billion threshold per issue.

Buybacks allow the Treasury to repurchase outstanding government bonds directly from the market, which can help support prices and dampen yield volatility during periods of stress. The expanded program came as stocks staged a late-week recovery: the S&P 500 and Russell 2000 both advanced on Friday, August 21, even as Treasuries logged mild losses, according to Bloomberg market data.

Why Bond and Equity Markets Are Diverging

Capital.com senior market analyst Daniela Hathorn described the week’s dynamic as markets “ending the week on a softer tone after the relative calm of early August was disrupted by renewed pressure in global bond markets, another rise in oil prices, and growing uncertainty around the Federal Reserve’s next move.” She noted that higher long-term borrowing costs are increasingly challenging elevated equity valuations, even as U.S. equities pull back modestly from record highs.

This divergence — equities near record levels while bonds sell off  is unusual and reflects two different sets of investor concerns. Equity investors have remained focused on corporate earnings strength, particularly from large technology companies ahead of Nvidia’s closely watched August 26 earnings report. Bond investors, by contrast, are more directly exposed to concerns about the scale of federal borrowing, highlighted this week by the national debt crossing the $40 trillion threshold for the first time.

The Fed and Treasury “Working in Opposite Directions”

Wilmington Trust senior bond portfolio manager Wil Stith told Yahoo Finance that current conditions reflect “the Fed and the Treasury basically working in sort of opposite directions,” adding that the imbalance will likely require the Federal Reserve  which he described as having “the larger sandbox”  to adjust the federal funds rate rather than relying on Treasury market interventions alone to manage yields.

Notably, the bond market’s reaction to the Treasury’s buyback expansion was relatively muted; strategists described the move as being largely absorbed without a major rally, suggesting the underlying pressure on yields stems from factors, such as inflation persistence and debt sustainability concerns, that a buyback program alone cannot resolve.

What Comes Next

Markets are now looking to two major events in the days ahead: Nvidia’s earnings report on Wednesday, August 26, and the Federal Reserve’s Jackson Hole Economic Symposium, running August 27-29. This will be the first Jackson Hole gathering under new Fed Chair Kevin Warsh, whose public communication style and policy signals remain less established than his predecessors’, according to market commentary from Regards of Wall Street.

For investors, the key metrics to watch are the size and frequency of future Treasury buyback operations, movements in the 10-year Treasury yield, and any policy signals from Warsh’s keynote address. Continued yield volatility alongside record equity valuations would suggest the market imbalance identified this week has not yet been resolved.


Continue Reading

Trending